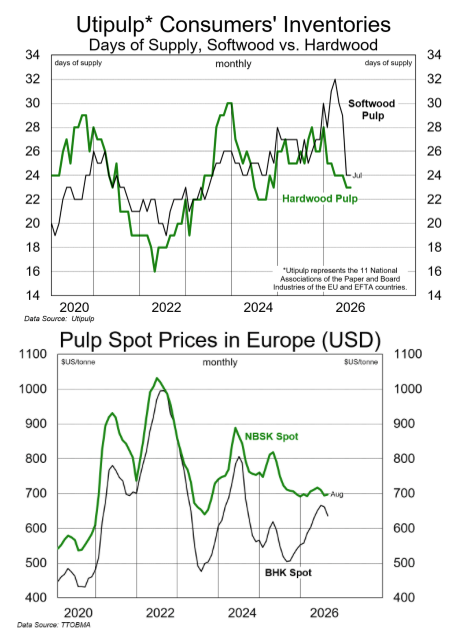
European NBSK inventories plummet, tightening supply
Report by ERA Research
European consumer softwood pulp inventories plummeted from a peak of 32 days of supply in March to 24 days in June/July, undoing inventory accumulation since late 2024. The analyst emphasizes that while NBSK prices remain at unprofitable levels despite robust European downtime from producers like Metsä and UPM, the cushion of sky-high consumer inventories has clearly reversed. Tighter European NBSK supply should support improving prices over time, with consumer restocking expected to drive the next upcycle. Mill inventories remain elevated, but incremental volumes could shift to hardwood as producers substitute furnish. Tighter conditions would provide a tailwind for UPM’s Fibres North group and Mercer’s German mills. On trades, there is no significantly NBSK-leveraged investable equity in the coverage universe, but higher prices would aid Mercer’s bondholder discussions, benefit Domtar ahead of large maturities, and deliver knock-on gains to Suzano.