No matches for this search
Try adjusting your filters or search criteria
Technology
ASM’s results were well ahead of expectations, but the bigger surprise is the outlook: the upward revision to this year’s revenue forecast pales beside 2027, where ASM is projecting growth of at least 35%. Demand remains supported by AI-related investment and customer capacity ramps, with strong activity at 2nm and 3-5nm and the first meaningful contribution from 1.4nm. Its served available market at 1.4nm should increase by a solid double digit vs. 2nm, alongside higher market share. the IDEA! also expects substantial operating leverage next year, with gross margins benefiting from newer systems and opex lagging revenue growth, driving adjusted operating income up ~50% to just over €2.0bn. At ~15.5x EV/EBIT, they see the valuation as very modest, underpinning a highly attractive investment case.
Technology
the IDEA! highlights a strong finish to 2025 for ASM, with Q4 revenue of €698m and bookings of ~€800m, both well ahead of guidance. The beat was driven by robust demand in advanced logic/foundry and solid spares & services sales, alongside a late-year rebound in China orders. Encouraged by the improved bookings trend, ASM guides for healthy revenue growth in 1Q26 vs. 4Q25. While the company’s backlog has come down from its record peak, the net sales-in-backlog ratio remains elevated at 4.2 months. the IDEA! also points to TSMC’s sharply higher capex outlook as reinforcing confidence that AI-driven investment will continue to benefit leading semiconductor equipment suppliers like ASM.
Nexperia dispute highlights Europe’s semiconductor dilemma
Technology
The escalating dispute between the Dutch government, China and chipmaker Nexperia has become a flashpoint in the global semiconductor power struggle. With parent company Wingtech already on a US trade blacklist and facing tighter restrictions, Nexperia’s plan to separate its Chinese and European operations is now in jeopardy. The export ban poses an immediate risk to Europe’s industrial supply chain, especially in the automotive sector. Finding and certifying alternative suppliers could take months, echoing the chip shortages of 2021/22. Strategically, it spotlights the West’s push for technological sovereignty and the Netherlands’ pivotal role in the China–West tech decoupling. Several (Dutch) companies could be affected including ASML, NXP, Philips and ASM International.
Is it finally time to buy Cyclicals?
At a time when economists are slashing year-end targets for major equity indices, star asset managers are forecasting the dollar’s demise, the collapse of the US economy and gold prices surging further, the real story has already begun and it’s the exact opposite. Recent sector rotation suggests markets are anticipating a brief global GDP contraction, followed by a rapid and robust rebound. Q1 results in Europe are strong. Companies are quickly adjusting supply chains to outmanoeuvre Trump’s tariffs. By early Jun, the tariff story will be old news and business will be almost back to normal. Stop overthinking and trust corporate agility. The real opportunity is in quality cyclicals - cash-rich, order-heavy, sector-dominating companies with rock-solid fundamentals. AIR’s top picks include Airbus, ASM International, Renault, Rexel, Schneider and Vestas Wind.
Technology
Report by
Cerundolo Investment Research
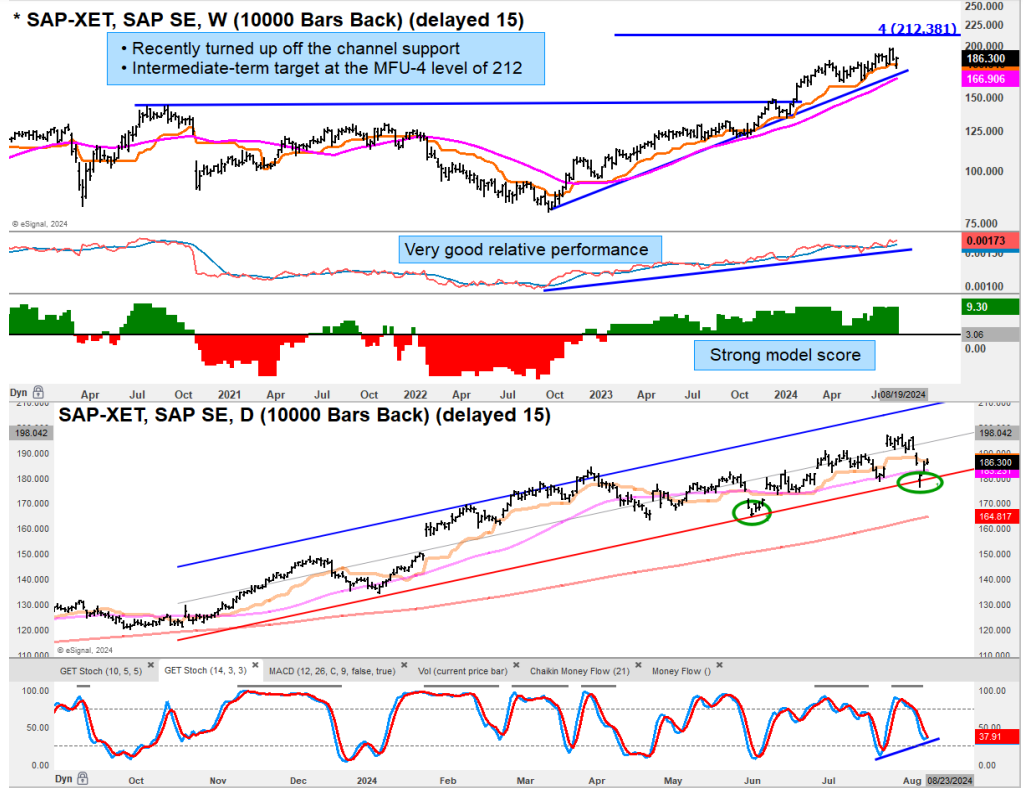
Guy Cerundolo provides a basket of long ideas in Europe. These stocks have good and improving multi-factor model scores. In addition to SAP (see chart) he also highlights companies including ASM International, Assa Abloy, CRH, Ferrovial, Philips, Rolls-Royce and Tesco.
Technology
Results were well ahead of market consensus. Furthermore, the sales mix was strong / contained a high contribution from China which resulted in an adjusted gross margin of 48.9% (at the high end of its mid-term guidance range of 46-50%). Order intake was outstanding, especially when accounting for the generally weaker market conditions. This year investments will be at an elevated level (€150-200m) and absorb a large chunk from the net cash from operating activities. However, in the years ahead FCF should accelerate based upon growing revenues, improving profitability and lower capex (€100-180m). Given ASM’s modest valuation and growth potential the IDEA! remains bullish.
Technology
While most investors in ASM are focused on the impact of macro headwinds in the semiconductor industry, Forensic Alpha’s systems noticed an odd movement in the profile of aged receivables - 20% of receivables are now past-due, with 10% now past due more than 30 days (vs. 2% in 2021). By the standards of the industry this is significant and should elicit more questions from investors around the current state of ASM's customers.