SK Hynix: The memory leopard will not change its spots
Technology
SK Hynix delivered an excellent Q3 and the near-term outlook remains exceptionally strong, with memory prices up 25%+ Q/Q and the company already sold out for 2027. DRAM demand next year is expected to grow faster than industry supply, while pricing should continue rising, setting up further strong revenue and profit growth; Richard Windsor suspects SK Hynix may even be lowballing its 2027 outlook. Where he disagrees is with the industry’s claim that memory cyclicality is over. Gross margins across memory are already around 86%, and while long-term agreements now cover 50% of SK Hynix’s 2027/28 production, Richard doubts they will prevent a price crash once supply eventually exceeds demand. AI-driven memory demand should keep that risk at bay for now, leaving the 12-month outlook excellent, but he sees 2028 as the point when the cycle could begin to turn.
China Advertising: AI widens the platform divide
Technology
86Research's latest channel checks sees them turn more cautious on China’s advertising outlook but more constructive on Tencent’s relative position. Ad growth fell short of expectations in Q3 and disappointing Double 11 demand points to further moderation, with 2027 likely to slow again as spending in AI products, smart devices and AIGC content normalises. At the same time, advertisers are shifting from headline GMV towards net transactions and measurable ROI, favouring platforms with stronger AI targeting, attribution and commerce integration. Tencent should benefit from deeper Alibaba integration, ADQ 3.0 and remaining Video Accounts traffic headroom, while Douyin remains strongest in end-to-end execution. Xiaohongshu and Bilibili also screen well, whereas Kuaishou, Baidu and Weibo face greater pressure. GEO adoption is accelerating, but near-term AI monetisation looks more likely to come through better ad efficiency than new chatbot advertising revenue.
Consumer Staples
BID remains an attractive way to play the structurally resilient shift towards eating out of home, with scaled distributors capturing more of the economics than restaurant operators themselves. Foodservice demand has compounded through the financial crisis, Covid, inflation, delivery apps and GLP-1 adoption, while barriers to entry in broadline distribution remain high because of route density, cold-chain infrastructure, purchasing scale and technology. BID combines that structural backdrop with record FY26 trading margins, light gearing, strong cash generation and a proven bolt-on acquisition model. Europe remains the main profit engine, while the UK offers the largest margin upside. Despite this, the company trades at just 16.5x FY26 P/E vs. materially higher US peer multiples.
EM Telcos: A rare buying opportunity
Communications
Higher inflation driven by the war in Iran has turned what were macro tailwinds for EM telcos into headwinds. But most of what the market is worrying about is noise, the fundamentals have never been stronger and history says not to wait for the macro to turn: after Ukraine, the sector bottomed a year before bond yields peaked. Sentiment is at a low and the market is about to be reminded of how good the fundamentals are via Q3 results. New Street believes this is the best buying opportunity investors are likely to see in EM Telcos for some time.
Indonesia: Good companies at bargain prices
The substantial de-rating of some of Indonesia’s best businesses, alongside low inflation and a depressed real effective exchange rate, has created a rare opportunity to buy market leadership, strong management and growth at attractive valuations. David Scott’s top picks are Bank Central Asia, Cisarua Mountain Dairy, Multi Bintang Indonesia, Sumber Alfaria Trijaya and Kalbe Farma. BBCA combines strong organic growth in an underbanked economy with improving efficiency and now trades at just 10.7x P/E. CMRY offers strong dairy and packaged-food brands, direct distribution and 30%+ ROE, while MLBI combines the iconic Bintang franchise with pricing power and high cash generation. AMRT’s dense Alfamart network and procurement scale underpin further store and online growth, while KLBF offers diversified healthcare exposure, broad distribution and established local brands.
Industrials
The stock trades at ~18x earnings, ~20% above its long-term average, despite growing structural competition and signs that near-term sales are being pulled forward. Milwaukee Tool has taken share with a better product priced 20-30% lower, while Harbor Freight has doubled its store base, expanded overlap with SNA’s hand-tool range and undercut prices by as much as ~80%. Younger mechanics also appear less attached to the brand, while franchisee and route counts continue to decline. Recent growth has also been helped by SNA’s largest-ever power-tool price cut: franchisees loaded up after a 30% discount, only for the company to subsequently launch a cheaper line to compete with Milwaukee. Rising franchisee receivables add to channel-stuffing concerns. The short thesis sees Q3 as potentially the last good quarter for two or three quarters; assuming at least a 15% EPS miss, it implies ~25% downside from current levels.
Financials
FSZ shares have fallen ~30% since Fighting Financials initiated their short on 9th Sep, but they see further downside as attention turns to the sustainability of its dividend. Their original thesis was that FSZ is a sub-scale, relatively undifferentiated asset manager caught between specialist boutiques and scale leaders, with five years of net outflows, declining AUM margins and unusually high leverage. Despite respectable investment performance, AUM has remained broadly flat as outflows offset market gains, while dividends and buybacks have materially exceeded earnings. Fighting Financials now argues that, if recent trends persist, FSZ will have to cut its dividend. At a more sustainable 50% payout ratio on FY26 consensus earnings, the shares would yield just ~4.5%, offering little compensation for the risks.
Consumer Discretionary
The return-to-office tailwind for US office furniture is fading just as HNI takes on substantial execution and financing risk from the Steelcase acquisition. Organic growth remains weak at both businesses, with industry growth increasingly driven by price rather than volume, making bullish expectations for a sustained rebound look too optimistic. OWS also questions the $120m+ cost-synergy target, arguing it looks ambitious relative to the seemingly narrow opportunities for savings across procurement, manufacturing and logistics. Steelcase has historically operated at lower margins than HNI, creating a separate risk that the combined company’s profitability falls short of Street expectations. Hearth adds another headwind, with fireplace installations in new homes declining and remodelling activity subdued. OWS models FY27 EPS of $3.35 vs. $4.70 consensus.
Communications
Craig Huber sees OMC’s Q3 results as further evidence that AI is not disrupting the top line, with organic revenue growth accelerating to 7.2% - the best quarterly performance since 4Q22 and, excluding the post-Covid rebound, since 3Q11. Adjusted EPS rose 22% Y/Y to $2.73, while adjusted EBITA reached $1.13bn and margin expanded to 17.6%; on a pro forma basis, core margin improved 200bps as Interpublic synergies and stronger organic growth outweighed reinvestment in technology and agentic AI. Craig now forecasts 2026-28 organic growth of 5.8%/5.0%/4.5%, EBITDA of $4.58bn/$4.85bn/$5.33bn and core EBITDA margins of 18.1%/19.0%/20.0%, with adjusted EPS of $10.33/$11.80/$14.40. He sees attractive risk/reward with the shares trading at just 7.0x/5.7x 2027/28E adjusted EPS. 12-month TP $100 (25% upside).
Utilities
ResearchGreece sees Admie as unattractive despite strong Q2 results at IPTO, its 51%-owned grid operator. The concern is that IPTO’s business plan remains demanding: H1 capex is running below FY26 guidance, yet investment would need to rise sharply in 2027-29 to deliver the €6bn programme and expand the regulated asset base to €7bn by 2029 from €3.3bn in 2025. That execution burden should keep leverage elevated, with IPTO net debt/EBITDA expected to peak above 5x. At the same time, Admie’s dividend yield remains subpar and the valuation is not compelling, with IPTO trading around 10-11x EV/EBITDA across 2026-29 versus grid and transmission peers at roughly 8.2x 2029.
Technology
ASM’s results were well ahead of expectations, but the bigger surprise is the outlook: the upward revision to this year’s revenue forecast pales beside 2027, where ASM is projecting growth of at least 35%. Demand remains supported by AI-related investment and customer capacity ramps, with strong activity at 2nm and 3-5nm and the first meaningful contribution from 1.4nm. Its served available market at 1.4nm should increase by a solid double digit vs. 2nm, alongside higher market share. the IDEA! also expects substantial operating leverage next year, with gross margins benefiting from newer systems and opex lagging revenue growth, driving adjusted operating income up ~50% to just over €2.0bn. At ~15.5x EV/EBIT, they see the valuation as very modest, underpinning a highly attractive investment case.
Technology
Taiwan's ban on China-made glass fiber yarn keeps Taiwan laminate plants buying E-Glass locally through at least 2028, and JNK's research indicates Nan Ya Plastics Corp, the largest local supplier, holds the pricing power. The laminate makers behind high-end AI boards, including Elite Material Co Ltd, have asked for an exemption, but JNK sees one as unlikely while Nanya is still adding capacity. JNK estimates Taiwan's E-Glass shortfall could approach half of demand in 2027 as local glass makers shift lines to Low-Dk fiber. The main risk is AI server customers moving laminate volume offshore as the cost gap widens.
Consumer Discretionary
Alibaba Group Holding Ltd is pivoting from acquisition-led expansion to disposals and artificial intelligence, redirecting capital toward AI infrastructure and cloud whilst streamlining non-core assets. VRS highlights that external Cloud Intelligence revenue expanded 40% Y/Y in the March 2026 quarter, yet heavy investment is depressing near-term economics: FY26 adjusted EBITA dropped 56% to RMB76.4bn as free cash flow reversed to an outflow of RMB46.6bn following the group’s commitment to invest at least RMB380bn in AI and cloud infrastructure over three years. Meanwhile, domestic marketplaces have lost share to PDD Holdings Inc and Douyin, driving heavy quick-commerce spend. Valuation multiples have compressed markedly, with the shares trading at 14.87x P/E and 10.43x EV/EBITDA on 2025 figures against an asset base carrying negative net debt of USD10.06bn. VRS sets a weighted target price of USD150.56 (37.20% upside) by blending a two-stage DCF valuation of USD132.61 (60% weight; 20.84% upside) with a peer group valuation of USD177.49 (40% weight; 61.73% upside).
Consumer Discretionary
Management was clear that market conditions have deteriorated over the past 3 months, with higher interest rates, inflation, gas prices, and tougher housing affordability. Yet Lennar Corp persists with increasing incentives and sacrificing margins to maintain even-flow production. This strategy risks slow-motion financial “suicide”, as there is no natural bottom to margin degradation when chasing demand at affordability. This pressure stems from their land bank structure; unable to renegotiate take-down pace, Lennar must buy lots and burn inventory or incur higher option fees. FY26 EPS is forecast at USD4.80/share (down from USD5.47/share), with FY27 lowered to USD4.54/share (down from USD6.38/share) as margins compress under 7% interest rates. LEN trades at 16.3x FY26 P/E vs 16.1x for peers, and 1.04x adjusted tangible book value vs 1.35x for the group. Fair value estimate is USD68/share vs GAAP book value of USD91/share.
Industrials
Following analysis of its FY25 annual report, Ed Steele and Shailja Periwal trim their Sandvik AB score to 23/60 from 25/60, principally reflecting FY25's much reduced level of stripped-out restructuring expense. Ed and Shailja calculate that stripped-out costs represented 4% of PBT adj in FY25 (ex M&A-related items) down from 13% in FY24, whilst stripped-out restructuring costs fell to 2% from 11%. Offsetting, they flag compressed balance sheet bad debtor and inventory impairment provisions, with bad debtor provisioning falling to 3.1% of gross receivables, a 10-year low. The gap between provisions expensed above the line and used or released moderated to 3% of PBT adj. Governance concerns persist: only three of ten directors clearly meet independence requirements, non-audit fees to PwC remain above average at 15%, and whistleblower reports rose 19% to 518 cases with a higher substantiation rate.
It’s playing out as sustaining technology, not disruptive
NYSE parent Intercontinental Exchange Inc filed with OKX for a 24/7 venue trading digital versions of 60-plus stocks, NVIDIA Corp and Space Exploration Technologies Corp among them, and Securitize Inc launched digital shares of 12 US companies. While consensus views this as market structure disruption by blockchain upstarts, it is playing out as sustaining technology: ICE keeps the listing, Robinhood Markets Inc keeps the customer, and the SEC keeps the gate. Like ETFs, the economics belong to license and distribution owners rather than plumbing vendors. The same split shows in listed crypto names: HOOD delivers a 43.9% operating margin and 23.6% ROE, while Coinbase Global Inc sits at negative 13.9%. With record September trading reaching USD$15.6bn (+16.4% M/M), revenue lands on a regulated broker priced at 48x earnings. Exposure rests with after-hours venues, market makers and custodians reliant on a 4pm market close, not disrupted exchanges.
Technology
Global Mining Research upgrades First Quantum Minerals Ltd from sell to hold, arguing that severe peer underperformance leaves investment metrics more compelling, while headline confusion over Cobre Panama obscures what appears to be a preference for a new operating agreement. Although news agencies latched onto the Commission’s recommendation for an “orderly closure”, the report is clear that the state cannot afford to fund closure or international arbitration, with First Quantum retaining the right to recommence ICC proceedings (>USD27bn). GMR assumes no full restart and continues to ascribe a conservative USD2bn risked option value (a 1 in ~5 chance). A recommissioning phase treating 38Mt of stockpiles offers a potential window until ~2H 2027 to reach an agreement, while the environmental audit failed to identify any material non-compliance. On this basis, the shares trade at 1.1x spot P/NPV10, 9.2x 2027E EV/EBITDA and a 4.7% FCF yield, with net debt/EBITDA falling to ~1.4x by 2030E. David Radclyffe sets a 12-month target price of C$39.60 and rates the stock HOLD.
Greek Banks: Solid fundamentals, less valuation headroom
Financials
Ahead of Q3 reporting, ResearchGreece notes that Greek banks offer solid fundamentals driven by high-single-digit volume growth, rising fees and healthy asset quality. However, with the sector trading at 1.59x and 1.46x P/TBV for 2026 and 2027 while offering 5.5% to 6.7% distribution yields, there is less valuation headroom. The firm favours National Bank of Greece SA, Bank of Cyprus Holdings PLC, Piraeus Bank SA, and Optima Bank SA. NBG and BoC are preferred for their straightforward balance sheets, strong capital ratios, and high distribution yields. Optima leads across almost every profitability component with superior earnings growth, while Piraeus offers a compelling risk/reward profile. Sustaining business lending above €9bn a year could prove challenging despite European funding initiatives. NBG and BoC earn OWN IT ratings with TPs of €19.3 and €12.2, while Piraeus and Optima hold TPs of €11.1 and €14.6 respectively.
Buy Cipher Digital Inc into convertible-induced weakness, viewing its USD850m 0% convertible (upsized to USD1bn via a USD150m greenshoe) and offer to equitise part of its 2030 notes as a rational funding move. The financing meets an acute near-term cash need ahead of data hall completions in 4Q26 and 1Q27, unlocking September’s Barber Lake extension, where a second 10Y lease adds USD5.2bn in revenue. The original 10Y lease cost USD2.2bn to build against USD3.9bn in revenue. With additional costs of USD734-759m, partly from tenant change orders, and only 50% of the tenant’s USD375-400m overrun share recovered via rent, Cipher is investing a net ~USD550m more. Only USD832m of its USD4.6bn cash at 2Q26 was unrestricted. With credit markets difficult, the convertible with capped calls limits dilution to 5-6%, versus 10+% for straight equity, locking in an attractive return on capital.
Consumer Discretionary
Bennett Cheer sees Domino's Pizza Inc as an active short ahead of the 3Q print, citing diminishing returns from promotional discounting, deteriorating run rates, and the absence of a credible driver for a back-half inflection. September's pullback in national deals exposed severe promotional reliance; card transactions plunged 430bps QoQ and foot traffic decelerated 340bps to 1.0% YoY as order counts broke down. Domino's operates as a barbell on order count and ticket, but Bennett warns that trading order volume for ticket squeezes franchisee profitability, supply chain volumes, and unit economics, with international operations offering no offset. Management already trimmed US net new store targets to ~175, and adding units into slowing comps risks cannibalisation. With 3Q US same-store sales tracking at -0.2% versus consensus at 0.73%, the full-year low-single-digit guide appears untenable. He models 2027 EPS at USD19.99againsttheStreetatUSD20.82; a multiple derating from 14.5x to 13.0-13.5x PE indicates downside to USD260toUSD270. Rating: Best-idea short.
US Midcaps, two years on
Industrials
Kailash Capital Research argues that midcap allocations have shrunk to an unprecedented 19.4% of the Russell 1000, setting a fresh six-decade low beneath the dot.com trough. Although the relative trade lagged by 3.6% since year-end 2024 (Russell 1000 up 32.3% vs. 28.7% for midcaps), valuation spreads have stretched right back to dot.com peak extremes. The Russell 1000 trades at 3.3x sales (the 99.9th percentile historically) versus 1.7x for midcaps, leaving the relative price-to-sales multiple at 1.9x. Crucially, the largest 50 stocks trade at 6.0x sales, matching the dot.com record of 3.5x the midcap sales multiple. Sector concentration has also intensified, with IT expanding to 36% of the large-cap benchmark, whereas midcaps offer broader US economic exposure led by Industrials at 17%. Kailash Capital Research reiterates funding midcaps by trimming mega caps, ranking AES Corp (AES), Cheniere Energy Inc (LNG), Popular Inc (BPOP), Axis Capital Holdings Ltd (AXS), and Halliburton Co (HAL) at the top of their 25-stock screen.
Technology
Meta Platforms Inc has launched its flagship closed models, Muse Wonder and Muse Wonder Full, retaking the high ground in AI benchmarks and addressing software generation to monetise compute against Anthropic PBC. Richard Windsor argues there is no moat in models; the ecosystem battle will instead be decided by ownership of the user touchpoint, where Meta holds an entrenched distribution advantage across its 3bn global users. Muse Wonder will power the core of Meta's consumer AI services, with the Muse agent already topping Apple Inc and Android download charts. Richard expects the maturing agent ecosystem to consolidate down to three or four dominant players to avoid commoditised returns, positioning Meta ahead of rivals like OpenAI Inc and Anthropic. The traction of Muse alongside enterprise compute monetisation underpins a valuation of at least USD$770 per share, where he maintains his position.
Muted US tariff relief fails Canadian lumber
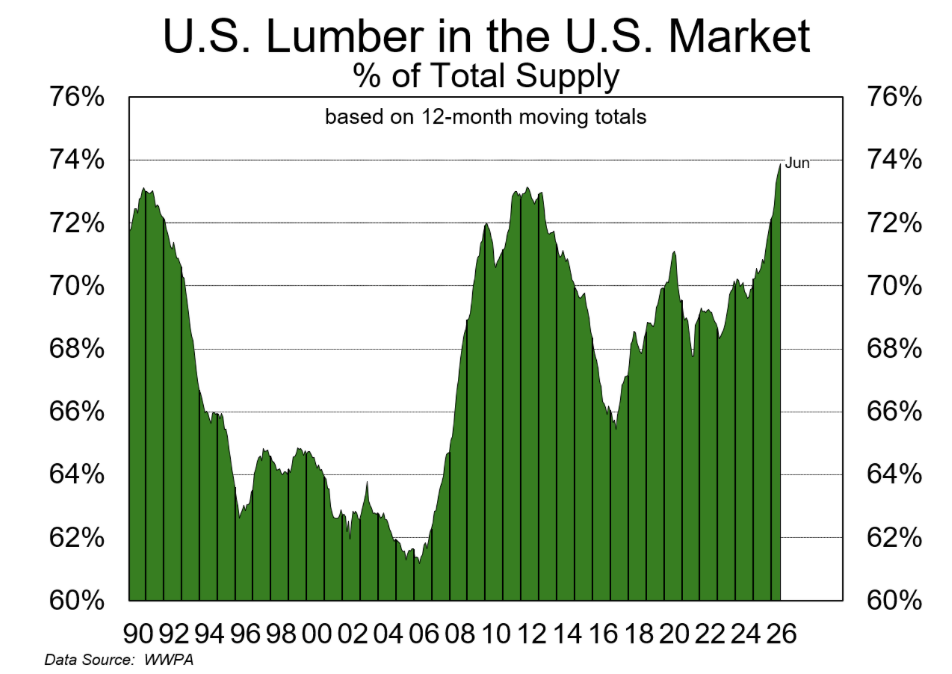
A ~10% reduction in combined anti-dumping and countervailing duties will not trigger a wall of wood across the 49th parallel, as Canadian exporters confront slumping demand and elevated structural costs. Following the US Department of Commerce seventh administrative review, final rates broadly match preliminary figures, lowering the combined All Others rate by roughly 50bps and WFG by almost 1%. However, with 10% Section 232 tariffs remaining in place, the combined duty and tariff burden hovers around ~35%, leaving US market share at a new high. Median cash costs for Northern BC commodity sawmills fall from USD530 to approximately USD495, still well above current Western S-P-F 2x4 prices of USD450. While lower-cost mills in Alberta, Ontario, and the Maritimes may pull back into the black, caution remains urged on Canadian lumber names against rising mortgage rates and slowing US homebuilding activity.
Altcoin Season Isn't Over, but the Money Is Rotating
Altcoin season is not over, but the money is rotating, as Bitcoin dominance climbs to 59.6% and tactical models switch back towards favouring the primary benchmark. Market breadth remains historically constructive, with 78% of tokens trading above their 200-day moving average and the proprietary altcoin season index holding in the 90th percentile at 56%. However, median correlation to Bitcoin has compressed to 50% across a six-month stretch below 60%, approaching prior cyclical peaks. A further drop in correlation towards 40% to 45% would signal an explicit profit-taking trigger, whilst a breach above 60% indicates altcoin season has formally concluded. Capital is actively rotating into fee-generating exchange tokens on Solana, Base, and TRON, whilst dumping legacy Ethereum DeFi protocols. Maintain core exposure to Bitcoin alongside sectors showing broadening breadth and weakening correlation, specifically Infrastructure, select DeFi venues, L1s, and L2s, whilst avoiding speculative rebounds across Meme, Gaming, and CeFi tokens.
Paybacks aren’t the impediment
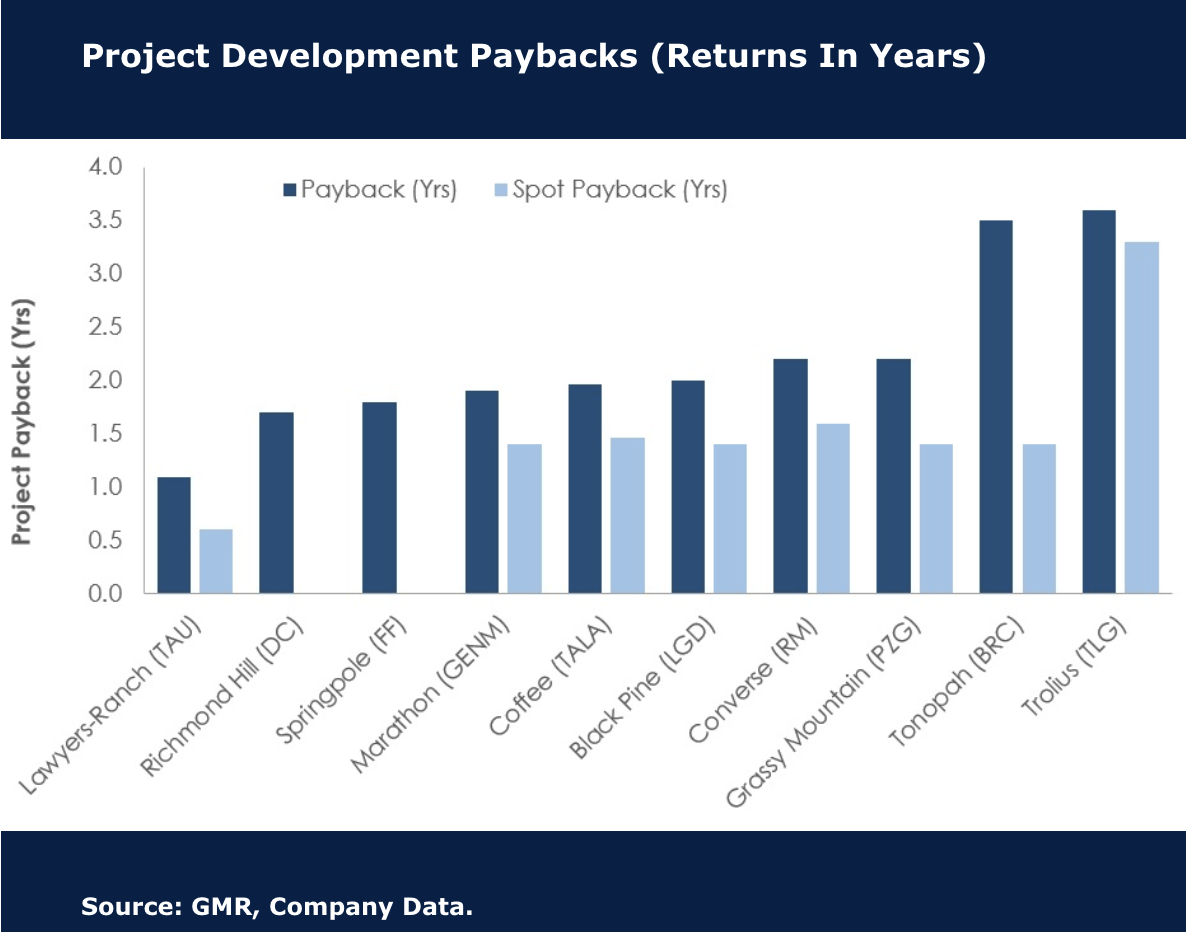
Paybacks aren’t the impediment to production growth across precious metals and copper, writes David Radclyffe following the Mining Forum Americas in Colorado Springs. Across ten sampled developers, base case paybacks averaged ~2.2 years (ranging from ~1.1 to ~3.6 years), falling closer to ~1.6 years at spot prices or US$4,000/oz. These low paybacks imply robust IRRs and favourable NPV/capex ratios, confirming that financial return metrics are not restricting development; rather, study completion timelines and permitting processes remain the key bottlenecks. Meanwhile, structural inflation has elevated capital intensity, which averaged >US$100M/Mt of annual processing capacity. Simple open pit heap leach projects sat at the lower boundary, whilst small underground operations with complex cyanidation exceeded >US$250M/Mt, and Grassy Mountain surpassed >US$300M/Mt. Radclyffe concludes that whilst spot economics provide compelling incentives to advance discoveries into production, statutory permitting, social licence, and study timelines ultimately dictate development schedules.
Can Saudi deliver oil?
James Burdass says that the market may be overestimating Saudi Arabia’s ability to convert spare production capacity into deliverable crude when several connected conflict theatres threaten its processing facilities, transport infrastructure, export terminals and maritime routes at the same time. At the same time, renewed fighting in Yemen and threats to Red Sea shipping have created additional uncertainty around Saudi Arabia’s alternative export route. Its East–West Pipeline transports crude from the kingdom’s eastern oil-producing region towards Yanbu on the Red Sea, reducing its dependence on the Strait of Hormuz. Yet if Gulf infrastructure and Red Sea shipping are threatened simultaneously, the alternative route could become less effective at precisely the time it is most needed. James points out that the key investment question is how reliably could Saudi Arabia maintain exports through a sustained and geographically broader security crisis.
Yemen: War and security
The security environment around the Bab al-Mandab Strait has changed considerably. An advance by Yemen’s Houthi rebels in September saw the Iran-backed movement seize a number of strategic locations across the country’s west coast, most notably the port city of Mocha. However, a counter-offensive by the Yemeni government (alongside Saudi air support) in early October now appears to have partly eroded the Houthis’ gains. While fighting continues, the Houthis retain considerable missile, drone and maritime capabilities to threaten shipping and Saudi infrastructure. The escalation is increasingly important for reasons extending well beyond Yemen. It has reopened questions around the limits of US security guarantees to Gulf partners. Furthermore, it sits at the intersection of overlapping conflicts stretching from Iran and the Gulf through the Red Sea and into Sudan, Ethiopia, Somalia and Somaliland. The crisis accordingly underscores the ongoing development of an overarching conflict system straddling the Middle East and Africa.
South Africa: Longer term lower-yield regime still intact
South Africa’s yield curve has risen since March, with the SAGB 10-year yield now at 8.9% from just below 8% at the end of February. However, Peter Attard Montalto still sees the longer term lower-yield regime as intact, and almost all of this move has been US related inflation and real rates not SA equivalents. Despite the oil shock and the subsequent global bond sell-off, SA yields remain 150-270bp below levels from just 18 months ago. Looking ahead, Peter remains constructive on the long end despite the difficult macro backdrop. He now sees the 10-year ending 2026 around 8.6% from 8.9% currently, which is still well above our 8.2% forecast before the war, while we continue to see yields just below 8% end-2027. Peter retains his MPC view of the first cut now only in July next year, which should keep the short end stable, but risks remain strong for a 25bp hike in January if fuel prices continue higher and El Niño risks intensify.
The inflating EPS bubble offsets US equity derating
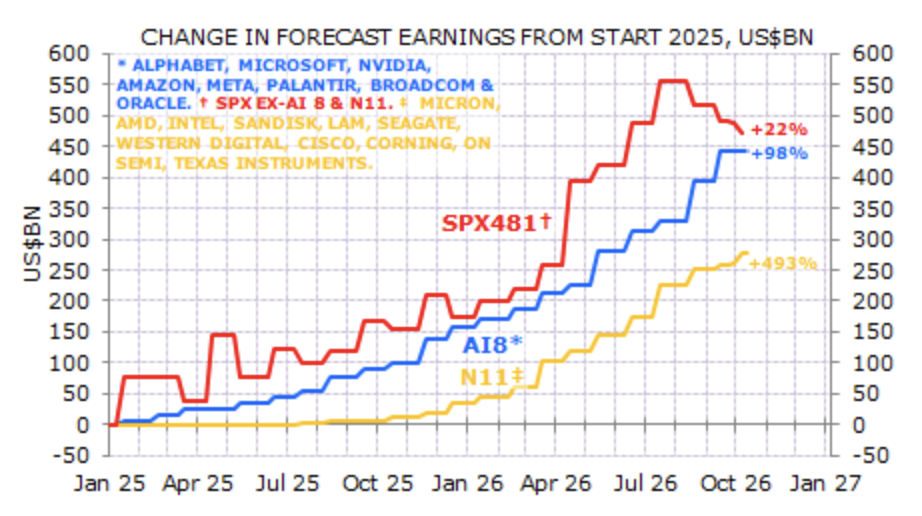
Gerard Minack argues that the September quarter reporting season will confirm the US is in the middle of an epic profit boom, offsetting valuation pressure from rising interest rates. Year-ahead forecast earnings have risen by USD1.2trn since early 2025, driven by the AI supply chain feasting on capex spending by AI providers, even whilst no one is making money from AI. Gerard expects earnings growth to continue offsetting multiple compression into 2027. Forecast earnings for the AI8 are up USD450bn, or 98%, while forecasts for 11 second-tier supply-chain stocks surged by USD$250bn, or almost 500%. The net effect is that AI leaders have outperformed whilst derating, leaving the Next 11 trading at a prospective PE below 14. If this is a bubble, it is an earnings bubble rather than a valuation bubble; the primary risk to medium-term US equity returns is not that valuation normalises, but that EPS growth does.
Are US stocks cheap?
The S&P 500 has pushed to all-time-highs through a pandemic, tariffs, the Iran war, and a 10-year Treasury yield spiking near 5.3%. Through it all, earnings have done the heavy lifting. Forward earnings growth near 40% is at a level investors have rarely seen. This year, earnings growth added more than 27 points to the S&P 500’s return, while a shrinking P/E took away more than 15. Even as the S&P hits record highs, the forward P/E of the index has fallen to 19, below its 5-year average. Tech, the market’s biggest sector, drove much of this drop. It went from the most expensive sector at 30.7x to below 22.5x in a year, as its earnings outran prices. Meanwhile, the 10-year yield is up ~475 bps from its lows, and it now pays about as much as the S&P 500’s earnings yield. If yields roll over, stocks at these levels look compelling. However, Francois Trahan says if yields keep climbing, earnings will have to continue carrying the market alone.
Contained pain in European credit
Long credit is fundamentally an embedded short volatility position. As realised and implied volatility rises, there is some pressure on some parts of the credit markets, corporate bond prices down, credit spreads wider. James Aitken notes the iTraxx Europe Crossover Index is at 315 basis points, out from 240 basis points in early July, but the acute strain sits where one or two leveraged players have been heavy sellers of the first loss tranche (0%-10%) and recycled the premium received into other credit exposures. The recent mark to market on these short credit protection exposures has been rough, ditto the decline in Virgin Media and Multiversity bonds. However, James expects it is not a systemic issue; the two most aggressive leveraged players hold abundant capital, maintain stable clients, and one just raised another USD$1.5bn. Expected European nominal GDP growth picking up means you cannot quit on European credit. Overall, it should be ok.
UK: Burnham dumps the triple lock
Graham Turner highlights that Andy Burnham dumping the triple lock to fund social care signals a prime minister willing to make tough choices, yet surging public sector pay remains the critical market flashpoint. While the gilt market has welcomed the reform, narrowing the 30-year Gilt-US Treasury spread, fiscal pressures are mounting rapidly. Rising global bond yields, FOMC tightening, and accelerating domestic inflation threaten to push annual debt interest well above £100.0bn in 2027, potentially surpassing the prior peak of £111.29bn. Graham warns that higher inflation risks an additional surge in public sector pay, which is already running at more than double private sector earnings growth. Fixing social care is a noble objective: but the real issue for public sector finances, and Gilts, will be whether the new prime minister has the resolve to rein in public sector pay, as inflation climbs.
Not all copper deposits are made equal
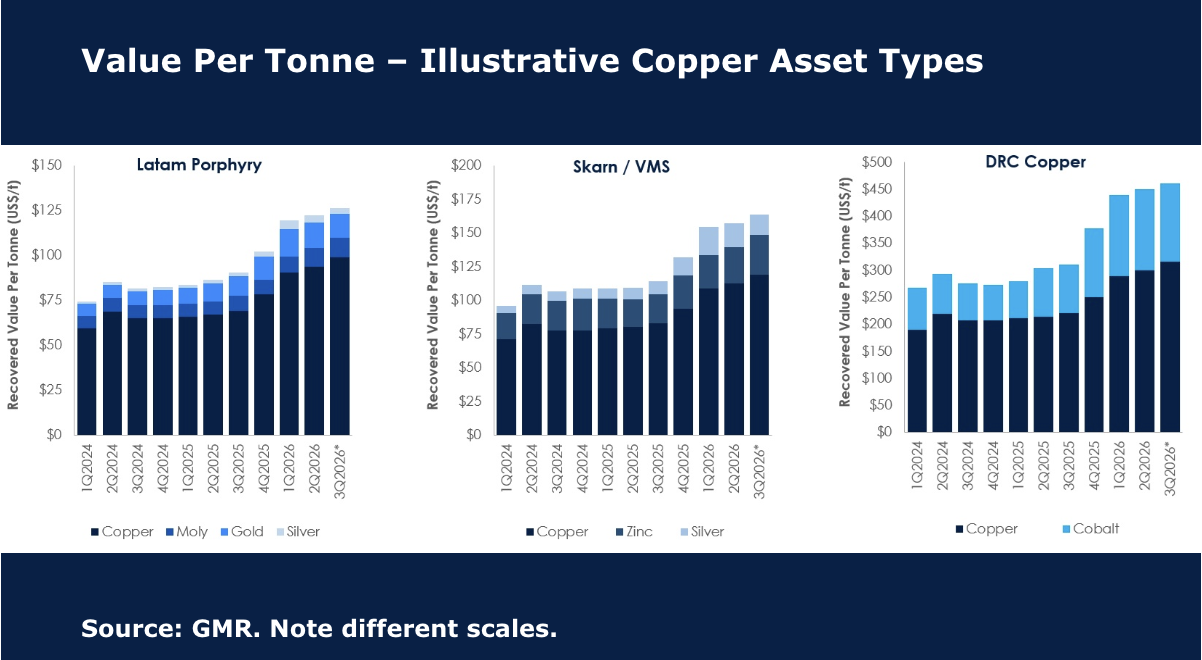
With only days remaining of 3Q 2026, David Radclyffe expects the copper price to show a record quarterly average, estimating LME cash has averaged US$6.37/lb alongside a 2% Comex premium. Whilst copper prices climbed 6% quarter on quarter, the team highlights significant credit volatility: gold slipped 5% and silver dropped 15%, whereas molybdenum strengthened 4% and zinc surged 10%. Across illustrative deposits, in situ recovered credit values range from 20% in Latam porphyries to 30% in the DRC, whilst Grasberg commands precious metal credits near 40%. David argues that the market focus on costs must be examined against value per tonne, with illustrative asset values increasing by 70% since 1Q24 to mark the highest in situ value across the period. Heading into quarterly reporting, primary challenges remain cost inflation and severe Chilean winter storms. Still, at least the margins are great.
Bitcoin to 140k minimum
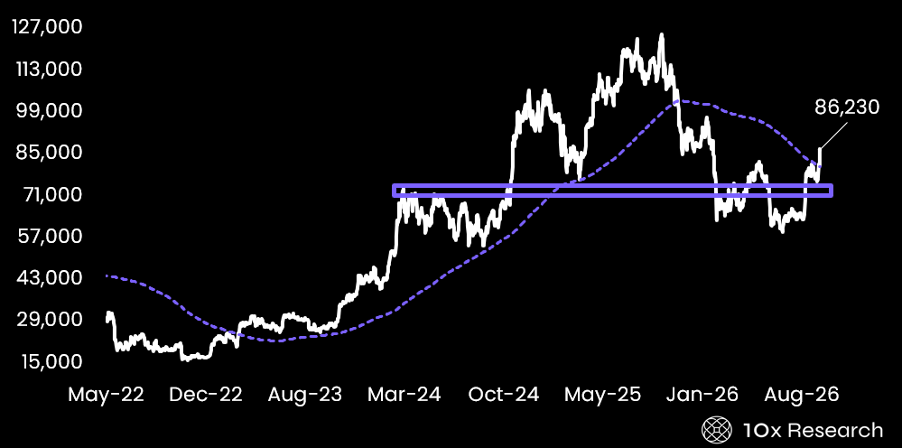
Markus Thielen points out that Bitcoin bottomed at US$63,000 in August, as he expected, during a quiet stretch when few people were paying attention. It has since climbed above 82,000. For now, the Fed is keeping money flowing, and that Markus says supports assets like Bitcoin. To judge how far this rally could go, he looks at the average price that investors (not miners) paid for their Bitcoin. That average is about 76,900 today, so the typical investor is sitting on a 12% gain. In past cycles, broad selling usually didn't start until investors were at least 85% in profit. That level is roughly 142,000 today. Markus therefore has a minimum target for this bull market of around 140,000 to 145,000. He doesn't expect to get there quickly, but the message is for people to stay invested and not let short-term news shake them out.
South Africa: SARB catch-up hike precedes long policy hold
The SARB unanimously lifted its policy rate by 25bp to 7.25% in a move the analysts characterise as a catch-up reaction after July’s policy mistake. Peter Montalto argues that the sudden return to a risk-management approach was driven by a belatedly raised fuel path flowing directly into core inflation, alongside two hawkish scenarios that spooked the committee. While the MPC’s updated quarterly projection model shifts to a higher-for-longer trajectory with end-2027 rates at 6.34%, Peter stresses that this move does not inaugurate a persistent hiking cycle. Instead, he maintain a baseline view of a prolonged hold, pencilling in the first rate cut for July 2027. However, late January carries meaningful upside rate risks should the fuel shock persist or El Niño conditions deteriorate, keeping policy firmly positioned at 7.25% through the first half of 2027.
Korea: Cost-push for now
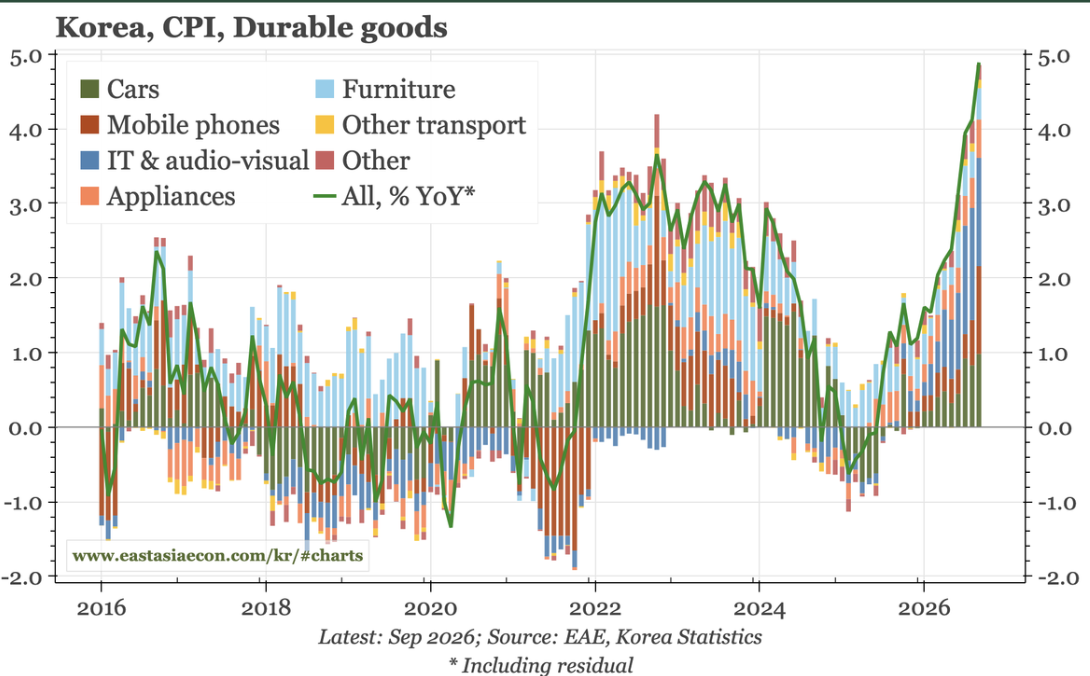
Korean headline CPI dipped in September as base distortions faded, but Paul Cavey warns that underlying price pressures are expanding. Cost-push forces dominate for now, driven partly by broad energy contributing 0.8ppts to the yearly headline print. Durables price inflation has hit its strongest pace since 2009, reflecting the pass-through of soaring semiconductor prices into downstream electronics. Computer prices are advancing at more than 20% year-on-year, and Paul expects upward pressure on durables to persist as export volumes and the trade surplus expand. Rising chip prices are driving nominal GDP growth to around 30% in the third quarter, creating an income surge that feeds households through stockmarket wealth effects, fiscal spending, and corporate bonuses. While weak labour data currently restrains domestic demand-pull forces, the BOK expects demand-side pressures to widen alongside cost shocks, keeping inflation risks elevated.
China: Moving defensive
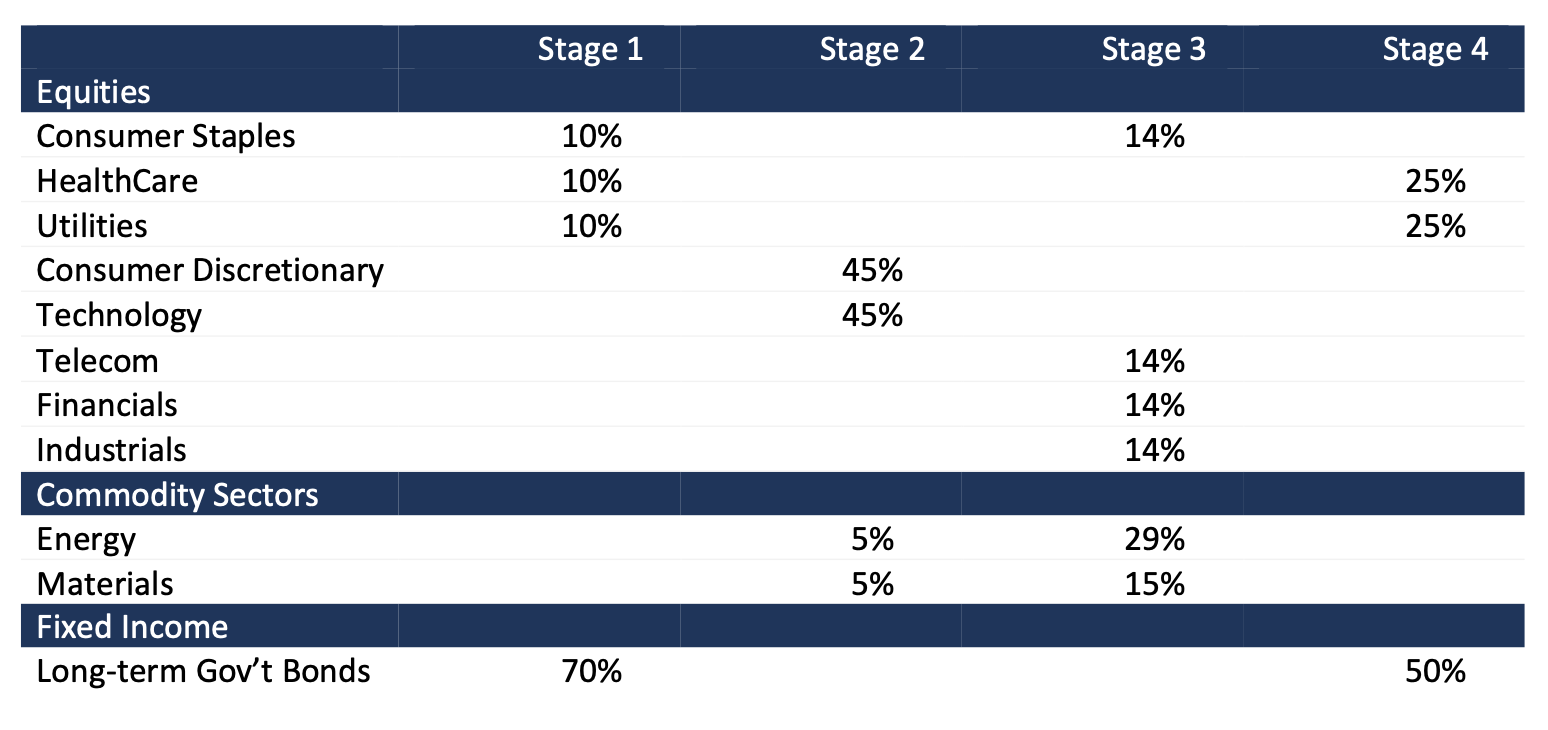
Frank Shostak updates China as rotating into the defensive Stage 4 of the business cycle, where early monetary headwinds emerge. With cyclical momentum turning fragile, Frank expects risk assets to face stiffer hurdles and advocates an explicit pivot towards defensive equity sectors relative to cyclicals. The monetary environment now proves far more beneficial for risk-averse debt, such as government bonds, over corporate credit and high-yield debt. In contrast, domestic liquidity measures are beginning to strengthen, suggesting that equity market momentum may be supported ahead. For August, the Chinese strategy gained 5%, outperforming the SSE Composite Index return of 4%. To manage the downturn, commodity exposures are eliminated entirely, setting allocations to basic materials alongside oil and gas to zero. Tactical portfolio parameters mandate 50% in 10-year government bonds, while remaining equity exposure is divided equally between utilities at 25% and healthcare at 25%.
The EM mirage
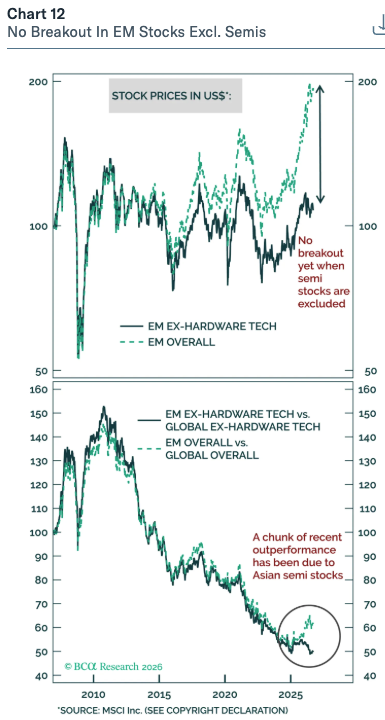
Arthur Budaghyan warns that underlying emerging market equity performance has been dismal, with headline gains driven entirely by three Asian semiconductor stocks comprising 28% of the MSCI EM index. Excluding hardware technology, EM equities have fallen to an all-time low relative to global peers. Arthur expects an impending downleg across the asset class as market breadth deteriorates severely, with just 43% of constituents trading above their 200-day moving average. Rising US Treasury yields are feeding directly into higher borrowing costs for sovereign issuers, pushing up the cost of capital in both USD and local-currency terms. For global equity portfolios, the stance is neutral EM against an underweight in the US. Within EM allocations, maintain relative overweights in China as a defensive play, India on improving capital flows, and Taiwan over Korea, while closing out the long China/short KOSPI tactical pair trade at a 15% loss.
Asian bonds: Stay A-float
Warut Promboon warns that fixed rate bonds and equities relying on discretionary spending will continue to underperform floating rate bonds as the Federal Reserve hikes into an oil shock. With headline PCE at 3.7% and WTI crude trading back near USD$100/bbl, the question has shifted from when the Fed cuts to how far it hikes, leaving the conflict's risk premium durable rather than transitory. Although Asian credit fundamentals remain resilient, rising risk-free benchmarks will exert upward pressure on regional borrowing costs, keeping yield-to-worst spreads widening rather than compressing. Warut advises investors to deploy a bond laddering strategy to avoid locking capital into prevailing rates while shifting directly into floating rate bonds that reset higher with each subsequent Fed tightening. For fixed rate allocations, hedge exposure using interest rate swaps, or harvest carry via short-duration credits such as State Bank of Mongolia 8.9% 2028 notes.
US: Examining the bond selloff
John Ryding expects the 10-year Treasury yield to finish 2026 at 5%, rejecting claims that recent violent selloffs signal unanchored long-term debt markets. Examining the move from 5.00% to 5.16%, he points out that the entire rise reflects higher real yields rather than runaway inflation expectations, with 10-year implied breakevens remaining anchored at around 2¼%. While Chair Warsh attributes rising yields to economic strength, hyperscaler capital competition, and geopolitics, John argues that the corporate sector has actually supplied net savings, leaving heavy government debt issuance and faster productivity growth as the primary culprits lifting the natural policy rate. He forecasts the Federal Reserve will deliver just one more rate hike in December before tightening again in March. With real 30-year yields already at 3¼%, he is sticking with the projection for a 5% yield at the end of this year.
An Aschenbrenner moment in rates
James Aitken argues that with US nominal GDP tracking 7.5% plus alongside a colossal global capex boom, current ten-year Treasury yields of 5.19% are not punishing, nor is US monetary policy remotely restrictive. Every crowded position is being hunted down in what James calls an Aschenbrenner moment in rates markets, driven by brutal position unwinds rather than macro fundamentals. While wary of picking a bottom in bonds without fiscal restraint, James highlights that asymmetric convexity and 5.5% long bond yields mean income is finally working for investors. For fully funded inflation-plus accounts, James views the ten-year US TIPS at 2.87% as a buy and a hedge against refining crisis demand destruction. He would also bet against the RBA delivering the three hikes priced by April 2027. Realised inflation plus 2.87% on ten-year TIPS feels all right: he wants to own that.
Technology
BTN questions how much of MXL’s recent improvement in sales and adjusted earnings can be sustained, particularly at ~50x adjusted EPS. Sales allowances have fallen from ~100 days of sales to just 25, including substantial reversals of prior accruals, materially supporting both reported revenue and pretax income. At the same time, equity-based compensation exceeds adjusted EPS and cash flow, while increased stock compensation may have added as much as 6.4c to Q2 non-GAAP EPS. Fully depreciated equipment provides a further estimated 5.2c benefit, while BTN estimates the unusually low 3% non-GAAP tax rate added another 2.6c - enough that MXL would otherwise have missed consensus. Meanwhile, sharply higher inventory purchase commitments point to a working-capital rebuild that could put further pressure on cash flow.
Top 20 UK SMID stocks
Their Systematic Analysis Model (SAM) ranks 290 UK stocks by combining revisions momentum, shareholder value and valuation to identify the most attractive opportunities. Hikma Pharmaceuticals and SigmaRoc are the latest additions to their top 20 ideas. HIK screens as unusually cheap for its quality, ranking in the top quintile on capital-returns valuation and trading at just under 8.5x FY2 P/E. ROCE has been improving since 2022, revisions momentum has strengthened for 8 months and is back above median, while a new CFO and strategic reset provide meaningful recovery potential. SRC has seen ROCE grind higher with OPAT margins increasing materially following the successful integration of CRH assets. It is still very cheap with the market implying it can only do 6% ROCE with the FY2 forecast at 8%. Revisions Momentum is back above median and improved significantly over the past 3 months. There is also scope for further M&A. TPs are 1900p for HIK and 216p for SRC.
Materials
Just three months after GMR warned that NST looked vulnerable to a takeover, Gold Fields has made an unsolicited A$27/share bid at a 22% premium. They identified GFI as one of the more logical strategic buyers, and the combination scores highly on GMR’s M&A rationale framework given the asset overlap, potential synergies, combined production of 4-5Moz/year and greater Australian weighting for GFI. NST has rejected the proposal as opportunistic, but at just 0.58x spot P/NPV5 it remains one of the cheaper large-cap gold names despite producing more than 1.5Moz annually and owning high-quality assets. GMR now asks whether this is simply the opening salvo, while pressure will be on the new CEO to deliver KCGM and show value within the portfolio.
NSE IPO: It’s not running away
Financials
At its IPO price of ₹1,785, NSE was valued at ₹4.42tn (US$46bn), equivalent to 40.8x Sree Capital’s FY27E earnings estimate. Despite its dominant market position, selling pressure remains even after listing. Derivatives regulation, CAS, RBI funding restrictions, competition from BSE / MSE and the potential NCL structural issue remain key overhangs. Future share-price performance will depend heavily on how the regulatory landscape for derivatives evolves.
Communications
SBG was a recurring topic across Astris’s recent Asia roadshow, highlighting how central the NAV debate has become for investors. Astris argues the group’s headline NAV substantially overstates what investors can realistically underwrite. Arm now represents ~64% of gross assets and has become both the biggest driver of NAV and a financing vehicle for further AI investments, while SVF2 / OpenAI accounts for another ~23% and carries a far less observable private-market valuation. Astris estimates realisable NAV at ~¥6,000/share, below the current share price, versus reported NAV of ¥12,686/share. This is the first of a three-part series: Part 2 examines SBG’s positioning for the AI cycle through three past big bets in Yahoo!, Alibaba and Arm, while Part 3 showcases Astris’s SBG model and swing-trade signal.
Materials
BASF’s reported €22.15 approach for EVK has been rejected as too low, but European Research believes €24-27 is achievable without stretching the valuation, with €25 their base case. At that level, BASF would pay 7.17x FY26E EBITDA, falling to 6.06x after €400m of estimated synergies, while RAG-Stiftung’s 43.8% stake would be worth €5.10bn. A partial RAG rollover into BASF could help bridge the gap while limiting the balance-sheet impact. They assign a 70% probability to a transaction, giving a probability-weighted value of €22.97, rounded to a €23 target price. That implies 15.8% upside from €19.84 vs. 8.9% downside to the €18.07 unaffected price.
Industrials
Investors are focusing too heavily on headline organic growth and not enough on the profitability and returns behind it. Reported underlying organic growth of c.3-4% has trailed peers, but Veritas estimates intentional post-acquisition shedding of lower-margin business has created a ~100bp volume headwind; adjusted for that, underlying volumes are only modestly negative and broadly in line with peers. That discipline has supported industry-leading ~33% margins, ~60bps of annual margin expansion since 2024 and attractive ~13% incremental ROIC. Veritas also sees Chiquita Canyon remediation costs declining and notes WCN remains ~6.5x cheaper than GFL on sustaining FCF. With the shares at their lowest premium to Waste Management / Republic Services in a decade, Veritas maintains a Buy rating and a valuation of US$198.
Ageing well & growing strong
Healthcare
An ageing US population provides a powerful structural tailwind for this healthcare-services company, with demand also supported by rising behavioural-health needs. New Constructs’ thesis is backed by a long record of execution: revenue and NOPAT have compounded at 8% and 11% annually since 2006, while Core Earnings have grown 12% compounded annually. The company improved its NOPAT margin from 5% to 9% in the TTM even as invested capital turns fell from 1.5 to 1.3. Rising NOPAT margins offset invested capital turns, driving ROIC from 8% in 2006 to 12% in the TTM. More recently, revenue and NOPAT have still compounded at 8% and 9% since 2021. With admissions and revenue per admission rising, strong FCF and shareholder returns, New Constructs sees a rare combination of durable demographic tailwinds, improving economics and a cheap valuation.
Financials / Business Services Idea Forum
Financials
While rate-sensitive names were well represented at MYST’s latest buyside event, they were struck by the large number of thematic ideas discussed. A handful were idiosyncratic / event-driven and, as has become the norm, most pitches carried an “AI winner or loser” angle. ACI Worldwide was the most popular idea pitched, with the biller sale seen as creating a “sexy” payments-infrastructure takeout target, while CoStar was considered the most contrarian, with Homes.com spending cuts expected to fuel an “EBITDA revision story” under the new CFO. Other ideas included Affirm, viewed as an underappreciated agentic-AI winner with rate fears already in guidance; Alexandria Real Estate Equities, where a biotech funding surge could drive lab-leasing inflection; and Brink’s, where NATL synergies and a shift towards higher-growth ATM services are seen as overlooked by the market.