No matches for this search
Try adjusting your filters or search criteria
Technology
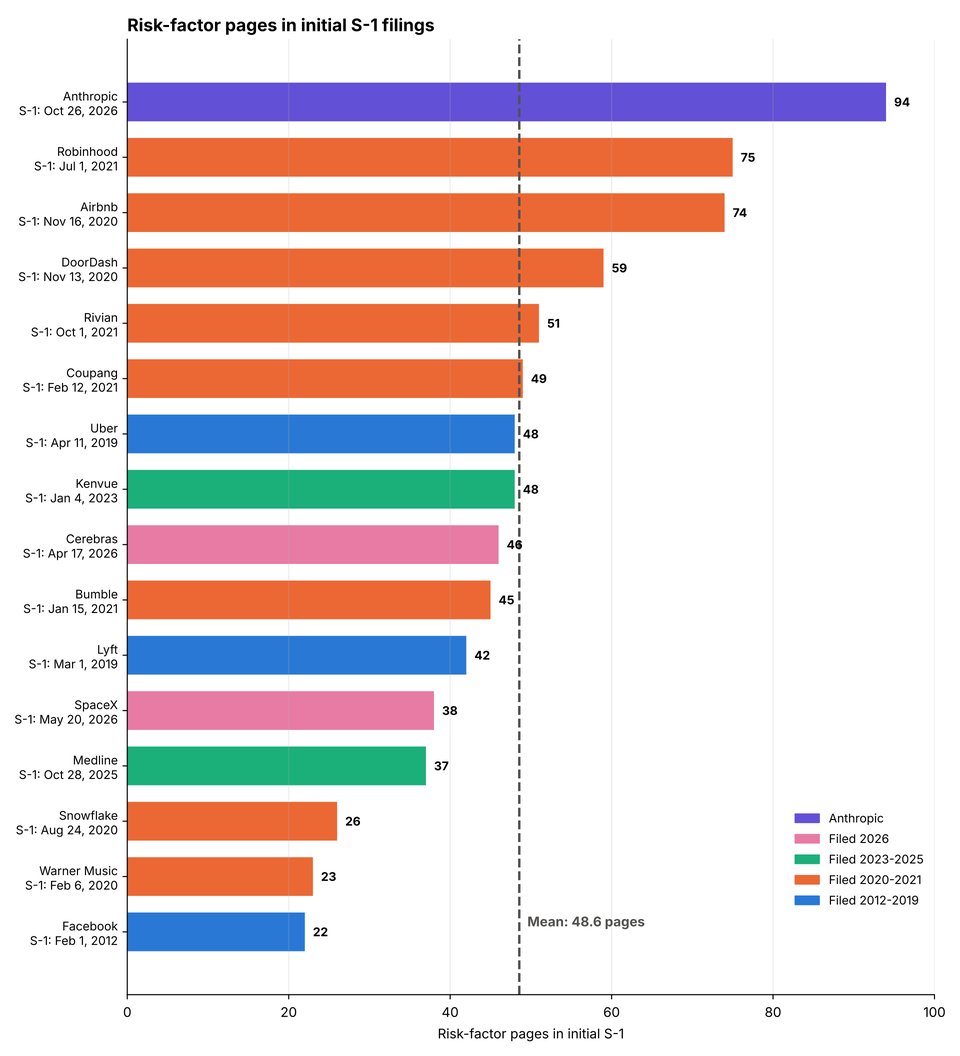
Anthropic’s S-1 contains one of the most extensive risk-factor sections footnoted has seen in a major US IPO. The company devotes 93 pages to risks, nearly twice the average for large US listings and well above recent IPOs such as Cerebras and SpaceX. The section has also grown materially from the 78 pages disclosed in Anthropic’s July filing. Several individual risks run for multiple pages, including constraints on compute availability and the possibility of models behaving in unintended, misaligned or autonomous ways. footnoted cautions that their comparison is not exhaustive across every S-1 filed since 2001 (when the SEC’s electronic repository of historical filings began), but among major IPOs over the past two decades, Anthropic stands out clearly for the scale of its risk disclosure.
AI Drug Discovery: Mapping the value chain
Healthcare
Hudson Labs has mapped the emerging AI drug-discovery ecosystem, providing investors with a structured view of where AI is actually being deployed across pharmaceutical R&D. Their work covers 353 companies (158 public and 195 private) spanning discovery CROs, lab tools, clinical-stage developers and large pharma, with each company classified by its position in the value chain, primary modality and the importance of AI to its business. Hudson has also compiled 705 sourced statements from earnings calls and filings on AI’s current and expected impact on R&D, giving investors a way to distinguish genuine adoption from broader AI narratives. The dashboard was developed alongside Citrini Research’s recent work with Anthropic on AI-enabled drug discovery and is now live on Hudson’s platform.
Technology
Meta Platforms Inc has launched its flagship closed models, Muse Wonder and Muse Wonder Full, retaking the high ground in AI benchmarks and addressing software generation to monetise compute against Anthropic PBC. Richard Windsor argues there is no moat in models; the ecosystem battle will instead be decided by ownership of the user touchpoint, where Meta holds an entrenched distribution advantage across its 3bn global users. Muse Wonder will power the core of Meta's consumer AI services, with the Muse agent already topping Apple Inc and Android download charts. Richard expects the maturing agent ecosystem to consolidate down to three or four dominant players to avoid commoditised returns, positioning Meta ahead of rivals like OpenAI Inc and Anthropic. The traction of Muse alongside enterprise compute monetisation underpins a valuation of at least USD$770 per share, where he maintains his position.
AI’s Minsky moment
Paul Krake warns that the market is edging closer to a Minsky moment in the AI infrastructure trade, as the industry builds out capacity around a development timetable its own leaders no longer believe is safe. Dario Amodei calling for a slower pace of frontier-model development directly challenges the thesis underpinning massive capex from Microsoft, Alphabet, Amazon, and Meta. Paul argues that while inference demand will endure, data-centre pipelines, power generation commitments, and Nvidia’s valuation rely heavily on accelerating frontier training requirements. He reckons that international agreements will fail because trust dissolves once AI is viewed through a national-security lens, leaving verification unworkable against China. This uncertainty jeopardises the timing and valuation of Anthropic’s potential USD$2trn IPO. With September seasonally weak for equities, any weakness in AI-linked assets could become self-reinforcing as investors recalibrate growth expectations lower.
AI: The wolf that cried wolf
The BCA team believes recent apocalyptic warnings from AI leadership are a calculated marketing stunt rather than genuine existential concern. Tech leaders are embracing fearmongering to justify astronomical private valuations, erect regulatory capture barriers against Chinese open-weight models, and rally Washington around national security. More critically, the team contend that OpenAI and Anthropic are on the hook for hundreds of billions in committed capex whilst running dangerously low on liquid cash. In this scenario, doomer hype serves as a convenient, face-saving corporate exit ramp to renege on massive commitments to build datacentres and purchase GPUs before unavoidable bills come due. For institutional investors, this performative handwringing signals that the peak in the AI capex cycle has arrived. Rather than demonstrating genuine corporate responsibility, frontier models are preparing to walk out on the check and dine and dash on the business cycle.
Healthcare
Hamed Khorsand views TWST as a growth-trap short, arguing the market is assigning software-like economics to what remains a capital-intensive life-sciences manufacturing business. The stock trades at ~17x 2026 revenue, well above profitable peers such as Agilent and Danaher, despite persistent cash burn and gross margins that Hamed believes are approaching a ceiling around the low-50s. Competitive pressure is also intensifying as integrated incumbents bundle NGS probes with broader reagent and library-prep offerings. He also sees the August share-price surge on Anthropic’s protein-design work as overdone, noting TWST was an independent evaluator rather than a strategic or commercial partner. Insider selling accelerated into the rally, while the recent equity raise highlights ongoing funding needs. 12-month TP $45 (65% downside).
AI: Circular financing
Paul Krake doesn’t see the unprecedented surge in circular GPU financing as fundamentally a leverage problem, but a question of long-term corporate demand and collateral resilience. While critics condemn Nvidia’s vendor financing as a late-cycle trick, history demonstrates that vendor credit allowed the building of rail, automotive, and aviation empires whenever secondary markets remained deep. However, GPU structures face acute risks: rapid annual silicon product cycles threaten Itel Corp-style obsolescence, custom chips lack resale markets, and customer funnels remain heavily concentrated compared to aviation leasing. Paul remarks that financial engineering is not the fault line, noting early constructive signals as Anthropic’s revenue run-rate expanded rapidly. When evaluating the sustainability of these massive structures, investors should look past the circular paper and interrogate corporate adoption directly: ask bears when they last spoke to a corporate about long-term AI strategy, because that is where the true risk lies.
Technology
Report by
Corto Capital Advisors
Corto argues TENB's sharp rerating is getting ahead of the fundamentals. Shares are up 50% YTD and 120% since early April as investors have become more comfortable that generative and agentic AI will not displace the company, a view reinforced by management’s Hexa AI strategy and partnerships with Anthropic and OpenAI. Corto is less convinced, arguing agentic AI could still reshape vulnerability management and that TENB has yet to show a corresponding growth inflection. Most key revenue indicators including organic growth, H2 guidance, new customer revenue, enterprise additions, NDE, deferred revenue and RPO continue to point to deceleration. With the shares now pricing in a growth rebound, Corto expects softer H2 trends, estimate risk and multiple compression, leaving significant downside from current levels.
European IT Services: Microsoft, OpenAI, Anthropic and AWS are not competitors
Technology
Gregory Ramirez views Microsoft Frontier Company as a pragmatic response to the challenge of deploying AI at scale rather than as Microsoft's entry into the traditional IT services market. While some overlap with systems integrators is inevitable, he believes the initiatives announced by Microsoft, OpenAI, Anthropic and AWS will expand, rather than displace, opportunities for IT services firms. Gregory therefore remains constructive on the outlook for European IT services, particularly Capgemini. As enterprise AI adoption accelerates, demand for implementation, integration and managed services should continue to grow. Investors have become overly cautious on the sector. CAP’s estimated EV/adjusted EBIT multiples of 6.4x for 2026 and 5.9x for 2027 do not fully reflect its medium-term AI growth potential.
Industrials
Arete initiates coverage with a Buy rating and DCF-based $401 2027E price target, reflecting the scale of opportunities in Space, Connectivity and AI. Starship’s path to full reusability could reduce launch costs to below $100/kg, while cooling and power appear resolved for Orbital Data Centres, with cost parity vs. terrestrial expected in the early 2030s. SSO launch cadence is likely the key scaling challenge. In Connectivity, Starlink has reached 12m customers and is adding c.800k/month, with Arete expecting a 2026E exit run-rate of c.$20bn revenue and c.$13bn EBITDA, helped by V3 satellites opening a larger suburban broadband opportunity. Mobile looks like a multi-billion-dollar long-term opportunity, but its inferior link budget and limited spectrum leave little room to disrupt terrestrial wireless. In AI, Anthropic and Google add $26bn p.a. in run-rate terrestrial AI infrastructure sales, while Orbital Compute could reach 29GW by 2035E and generate >$1trn of sales by 2037E.
What’s driving bonds, war or tokenmaxxing?
David believes it is a combination of both higher oil prices and the AI rally that has driven up real yields. The release of Claude Mythos reignited the AI trade, strengthening the view that AI will unleash a productivity boom in the economy, which may be one reason why long-term real yields have repriced higher. Another factor is the positive wealth effect associated with the AI rally, supposedly meaning that the Fed can focus more on the upside inflation risks posed by higher oil prices than on the downside risks to growth. However, David is sceptical of the rally continuing; frontier model capabilities are plateauing and companies are now imposing stricter budgets on AI token usage. The growth path Anthropic recently experienced could be unsustainable and the AI rally might be becoming even more narrow. It’s too early to buy bonds, but a steepener is starting to make sense again.
Special Sits Idea Forum
MYST’s buyside events continue to deliver impressive performance (~19% avg. alpha on highlighted ideas at their previous Special Sits Forum). Their latest event featured a high number of potential takeouts / M&A plays, business separations, several Media stocks and various AI-related companies. The most compelling ideas included:
Chemours (CC US) - Refrigerant share gains + “free kicker” from steepening China TiO2 cost curve. TP $46 (110% upside).
ITT (ITT US) - High-quality pumps pure-play experiencing positive mix shift. TP $284 (45% upside).
Valmont Industries (VMI US) - “Non-obvious” AI infrastructure play benefitting from utility pole pricing inflection. TP $709 (35% upside).
Fundrise Innovation Fund (VCX US) - AI / Anthropic proxy trading at ~10x NAV with upcoming lock-up expiry catalyst. TP $50 (75% downside).
Approaching peak AI hysteria
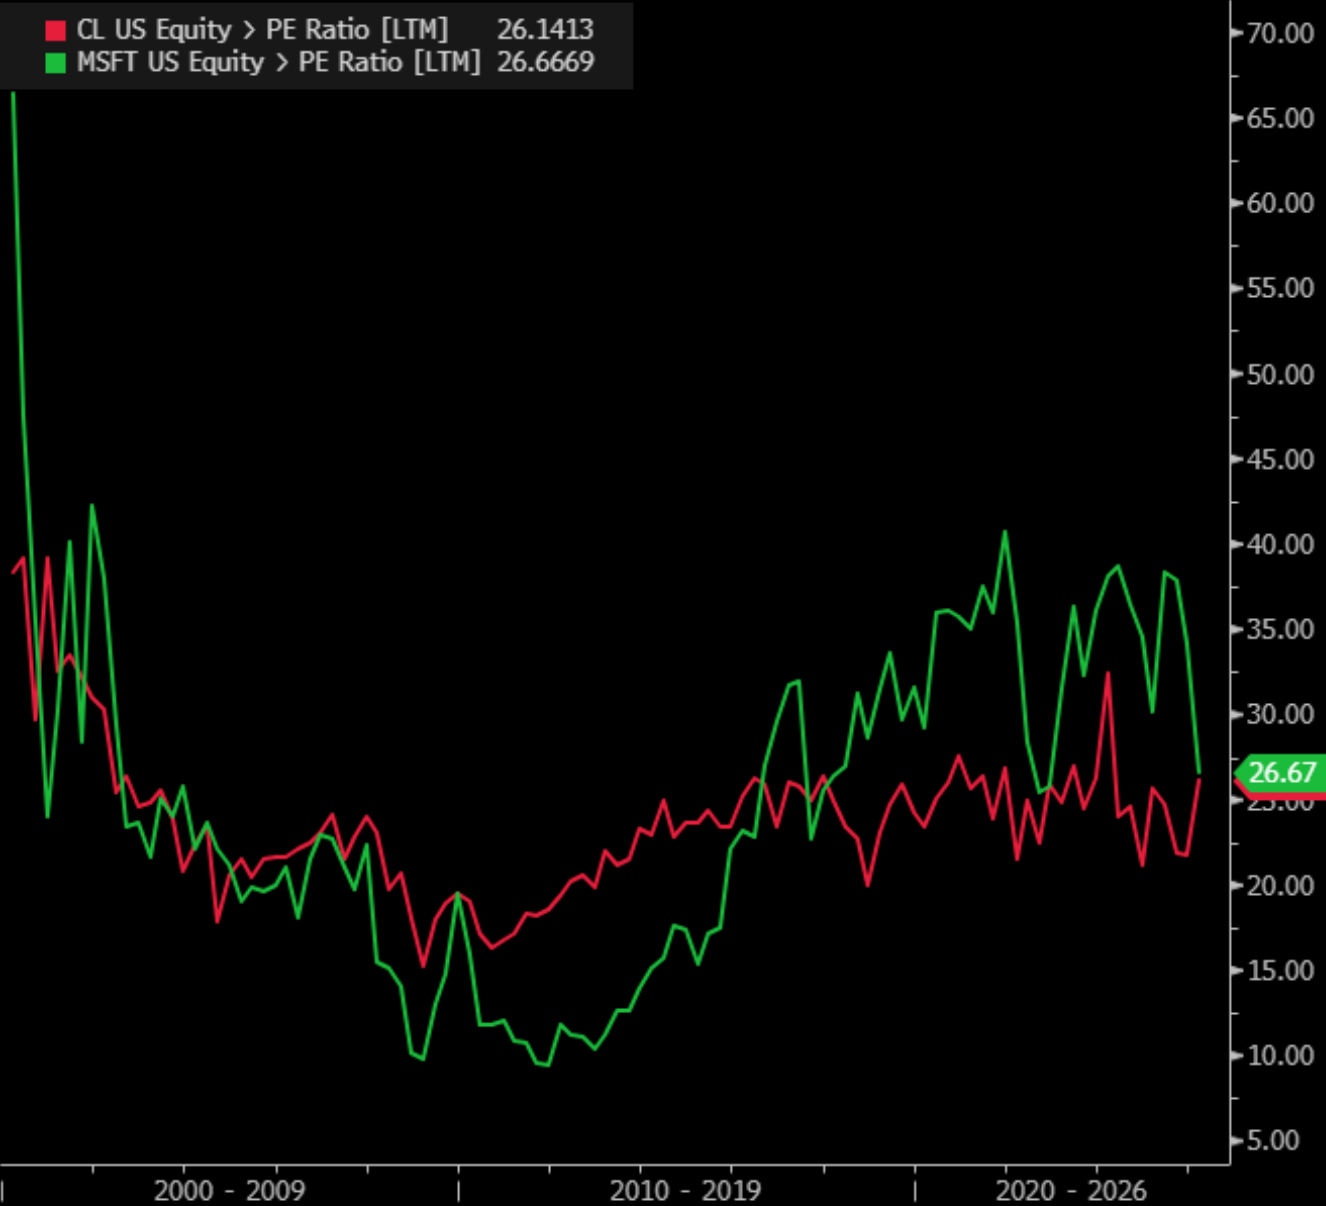
People are gregarious and instinctively follow the impulses of the herd, remarks James Aitken. The past two weeks have been a reminder of the mob mentality, and with dystopian projections on AI hysteria reaching millions of views, James believes we are approaching peak AI hysteria. Just remember when scouring the news: why am I reading this now and who benefits? XAI, Anthropic and OpenAI are all in windows to raise absurd amounts of money at lofty valuations, so it’s no surprise everyone is getting almost daily updates on LLMs about their improvements. DRAM, NAND and H100 rental prices suggest the AI juggernaut and associated memory shortage continues, yet so violent has been the recent shakedown that companies that would seem to have little risk of being disrupted by AI have been smashed, too. Just look at the current P/E of Microsoft (green) vs the current P/E of Colgate (red).
AI: The race to the bottom
One would have expected Anthropic’s latest innovation to be part of its premium tier, but the fact it is free is a sign that the race to the bottom, kicked off by Meta, is already underway. Richard Windsor sees it as a sign that the company is struggling to attract users to its platform in an already competitive environment. There are still no signs of the promised superintelligence on the horizon. Current expectations and valuations are unrealistic, and we will likely see the reset begin in the venture capital space as start-ups fail to meet their targets and go back to their backers for more money. Against this backdrop, everyone is going to take a hit, but the least pain is likely to be felt by Nvidia and TSMC. Richard prefers adjacencies of inference at the edge and nuclear power as the best way to get exposure to AI.