Technology
ACIW is being valued like a growth software company just as its core banking franchise faces a revenue cliff. Roughly 70% of EBITDA comes from legacy on-premise bank software, where customers are resisting price increases, simplifying tech stacks and, in some cases, moving processing in-house or to competitors. The recent license-revenue surge looks more like a renewal-cycle pull-forward than a new growth algorithm: LTM license and services bookings are declining double digits, banking backlog is only growing low single digits excluding an anomalous quarter (2Q25), and maintenance revenue is flat despite the license spike. With the customer base already saturated, limited cross-sell and doubts around an accretive Biller sale, consensus growth looks hard to achieve. TP $26 (50% downside) applying ~10x multiple to FY28 EPS of ~$2.65 (vs. $4.28 consensus).
Communications
Craig Huber sees OMC’s Q3 results as further evidence that AI is not disrupting the top line, with organic revenue growth accelerating to 7.2% - the best quarterly performance since 4Q22 and, excluding the post-Covid rebound, since 3Q11. Adjusted EPS rose 22% Y/Y to $2.73, while adjusted EBITA reached $1.13bn and margin expanded to 17.6%; on a pro forma basis, core margin improved 200bps as Interpublic synergies and stronger organic growth outweighed reinvestment in technology and agentic AI. Craig now forecasts 2026-28 organic growth of 5.8%/5.0%/4.5%, EBITDA of $4.58bn/$4.85bn/$5.33bn and core EBITDA margins of 18.1%/19.0%/20.0%, with adjusted EPS of $10.33/$11.80/$14.40. He sees attractive risk/reward with the shares trading at just 7.0x/5.7x 2027/28E adjusted EPS. 12-month TP $100 (25% upside).
Consumer Discretionary
Alibaba Group Holding Ltd is pivoting from acquisition-led expansion to disposals and artificial intelligence, redirecting capital toward AI infrastructure and cloud whilst streamlining non-core assets. VRS highlights that external Cloud Intelligence revenue expanded 40% Y/Y in the March 2026 quarter, yet heavy investment is depressing near-term economics: FY26 adjusted EBITA dropped 56% to RMB76.4bn as free cash flow reversed to an outflow of RMB46.6bn following the group’s commitment to invest at least RMB380bn in AI and cloud infrastructure over three years. Meanwhile, domestic marketplaces have lost share to PDD Holdings Inc and Douyin, driving heavy quick-commerce spend. Valuation multiples have compressed markedly, with the shares trading at 14.87x P/E and 10.43x EV/EBITDA on 2025 figures against an asset base carrying negative net debt of USD10.06bn. VRS sets a weighted target price of USD150.56 (37.20% upside) by blending a two-stage DCF valuation of USD132.61 (60% weight; 20.84% upside) with a peer group valuation of USD177.49 (40% weight; 61.73% upside).
Technology
Meta Platforms Inc has launched its flagship closed models, Muse Wonder and Muse Wonder Full, retaking the high ground in AI benchmarks and addressing software generation to monetise compute against Anthropic PBC. Richard Windsor argues there is no moat in models; the ecosystem battle will instead be decided by ownership of the user touchpoint, where Meta holds an entrenched distribution advantage across its 3bn global users. Muse Wonder will power the core of Meta's consumer AI services, with the Muse agent already topping Apple Inc and Android download charts. Richard expects the maturing agent ecosystem to consolidate down to three or four dominant players to avoid commoditised returns, positioning Meta ahead of rivals like OpenAI Inc and Anthropic. The traction of Muse alongside enterprise compute monetisation underpins a valuation of at least USD$770 per share, where he maintains his position.
Altcoin Season Isn't Over, but the Money Is Rotating
Altcoin season is not over, but the money is rotating, as Bitcoin dominance climbs to 59.6% and tactical models switch back towards favouring the primary benchmark. Market breadth remains historically constructive, with 78% of tokens trading above their 200-day moving average and the proprietary altcoin season index holding in the 90th percentile at 56%. However, median correlation to Bitcoin has compressed to 50% across a six-month stretch below 60%, approaching prior cyclical peaks. A further drop in correlation towards 40% to 45% would signal an explicit profit-taking trigger, whilst a breach above 60% indicates altcoin season has formally concluded. Capital is actively rotating into fee-generating exchange tokens on Solana, Base, and TRON, whilst dumping legacy Ethereum DeFi protocols. Maintain core exposure to Bitcoin alongside sectors showing broadening breadth and weakening correlation, specifically Infrastructure, select DeFi venues, L1s, and L2s, whilst avoiding speculative rebounds across Meme, Gaming, and CeFi tokens.
Guardians of the blue economy
Sophie Biro finds that developed economies are moving the blue economy from a policy aspiration to an investable asset class. Where developing economies make 60-90% of commitments contingent on external support, developed countries frame targets as unconditional domestic obligations, so investments sit within policy environments with binding regulatory commitments and greater policy predictability. Private capital dominates, and most sectors require no concessional subsidy. Offshore wind is now a core component of mitigation pathways, with GWEC projecting capacity to rise from approximately 83 GW in 2024 to more than 410 GW by 2035. The IMO Net-Zero Framework vote was postponed to October 2026, moving binding global carbon pricing for shipping to around 2028. Barbados’s USD 150 million debt conversion cut its borrowing cost from 7.2% to 4.9%, while Uruguay’s bidirectional sustainability-linked sovereign bond falls in rate when the country outperforms on targets and rises when they are missed. For investors, the opportunity lies in financing ocean-related infrastructure and navigating the evolving regulatory and governance architecture.
South Africa: SARB catch-up hike precedes long policy hold
The SARB unanimously lifted its policy rate by 25bp to 7.25% in a move the analysts characterise as a catch-up reaction after July’s policy mistake. Peter Montalto argues that the sudden return to a risk-management approach was driven by a belatedly raised fuel path flowing directly into core inflation, alongside two hawkish scenarios that spooked the committee. While the MPC’s updated quarterly projection model shifts to a higher-for-longer trajectory with end-2027 rates at 6.34%, Peter stresses that this move does not inaugurate a persistent hiking cycle. Instead, he maintain a baseline view of a prolonged hold, pencilling in the first rate cut for July 2027. However, late January carries meaningful upside rate risks should the fuel shock persist or El Niño conditions deteriorate, keeping policy firmly positioned at 7.25% through the first half of 2027.
Ageing well & growing strong
Healthcare
An ageing US population provides a powerful structural tailwind for this healthcare-services company, with demand also supported by rising behavioural-health needs. New Constructs’ thesis is backed by a long record of execution: revenue and NOPAT have compounded at 8% and 11% annually since 2006, while Core Earnings have grown 12% compounded annually. The company improved its NOPAT margin from 5% to 9% in the TTM even as invested capital turns fell from 1.5 to 1.3. Rising NOPAT margins offset invested capital turns, driving ROIC from 8% in 2006 to 12% in the TTM. More recently, revenue and NOPAT have still compounded at 8% and 9% since 2021. With admissions and revenue per admission rising, strong FCF and shareholder returns, New Constructs sees a rare combination of durable demographic tailwinds, improving economics and a cheap valuation.
Materials
The market’s view of Sumitomo Chemical is increasingly outdated, with investors still valuing it as a complex, commodity-heavy conglomerate despite a material shift in the business. Much of the apparent revenue weakness reflects deliberate exits from low-margin, capital-intensive activities rather than deteriorating demand, while the Petro Rabigh overhang has been reduced through a lower ownership stake and balance-sheet simplification. Yuka Marosek also thinks investors are misreading the earnings recovery: it is not simply cyclical, but increasingly reflects structural loss elimination and a richer mix of higher-quality businesses. Agro & Life Solutions and ICT & Mobility are expected to contribute 56% of FY3/27 core operating profit, while semiconductor materials benefit from high switching costs and long qualification cycles. Yuka therefore believes the market is applying the wrong multiple to the wrong earnings base.
Telecoms: The two-tier market widens
Communications
Astris expects the strong-two / weak-two divide in Japanese telecoms to persist and likely widen through Q2. KDDI and SoftBank Corp screen best, supported by network-quality-led pricing power and lower reliance on promotional spend to retain subscribers, while 20%+ growth in data centres and Cloud / AI provides an additional offset to core mobile pressure. NTT / Docomo is the key swing factor for the sector, with the gap between Q1 growth and full-year guidance implying a meaningful step-down in profitability as it defends share. Rakuten Mobile is the highest-risk name into Oct as its KDDI roaming footprint is reduced, with the exact post-Sep arrangements still being finalised and network quality the key catalyst investors should track. Given historically low Japanese churn, Astris would not expect a clean read on Rakuten’s post-roaming subscriber trend until the Q3 print in early Nov.
Healthcare
Chronic strength outweighs acute pain - the market is focusing too heavily on Kerecis and overlooking the resilience of the core franchise. Chronic Care, which represents ~75% of sales, continues to deliver ~7% organic growth, supported by high switching costs and leading market share, while Interventional Urology has also grown at a HSD pace. Kerecis remains the main problem, with outpatient activity hit by the new Medicare reimbursement regime, but inpatient growth remains healthy and management is now targeting recovery by 2Q27. Consensus has essentially given up on margin recovery, but AlphaValue thinks that is too pessimistic and expects gradual improvement as FX and plant ramp-up costs roll off. The shares are trading at their lowest valuation in more than a decade and offer a 5.3% dividend yield, the highest in the sector. TP DKK644 (55% upside).
Indonesia: Extremely hated to less hated
Back in June, the Variant Perception team flagged a cluster of LPPL crash-exhaustion buy signals as marking a capitulation bottom and a tradeable low in Indonesian equities, but they would now take profits as leading indicators have worsened and their tactical outlook models have turned negative. Indonesia growth leading indicators ticked down this month, while the core inflation leading indicator is trending higher. Bank Indonesia is also still prioritising the currency, which leaves little room to ease and results in a very high real policy rate that will start to weigh on domestic demand. Crucially, their tactical outlook model triggered a sell signal on Indonesian equities on August 21st, with the tactical forecast return turning negative again. Indonesian assets have gone from total capitulation to merely unloved, making this an opportune time to take profit on the equity tactical long.
India: Time to upgrade
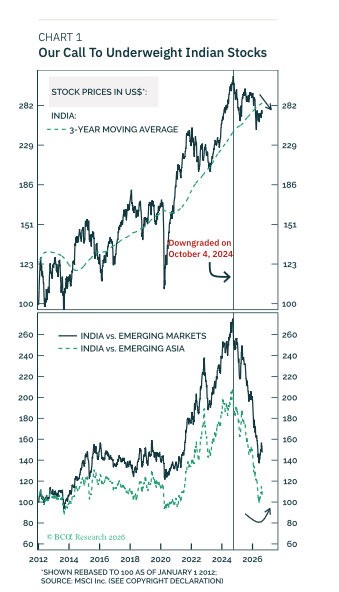
Brian Payne and Arthur Budaghyan argue that India has largely avoided the Hormuz shock, with fuel and fertiliser supplies intact and monsoon rains recovering. Consequently, they headline and core inflation to stay contained, asserting that the central bank’s next move will be a rate cut despite markets pricing in a 65-basis-point hike. Although absolute-return investors should not anticipate an outright equity rally, the analysts believe the bourse’s massive underperformance against emerging market peers is in a late stage. Dedicated EM portfolios should upgrade Indian equities to overweight and shift local bonds from neutral to overweight. In private markets, they advise leading with venture capital over private equity. Investors should now take profits on their short Indian stocks and long Chinese A-shares trade for a 44.5% gain, cut the short small-cap and long large-cap spread at a 16.8% loss, and buy unhedged 10-year domestic bonds.
Consumer Discretionary
The recent stock decline may suggest otherwise, but TSCO is a structurally stronger business than pre-Covid, supported by a larger needs-based sales mix, deeper customer engagement and store productivity that remains attractive despite moderating comps. Brian McGough views current pressure as cyclical, with discretionary weakness offset by resilience in the core business. He also pushes back on the idea that the pet category is “broken”, arguing assortment, value, digital/subscription and services initiatives can stabilise performance and rebuild share. Longer term, Brian thinks the Street is massively underestimating earnings power, helped by another ~800 stores and potential mid-to-high-single-digit comps when housing recovers. He sees ~50% upside over 18 months and a TAIL double on his base case model.
Consumer Staples
John Zolidis sees DLTR’s Q2 as evidence that its multi-price strategy is working, with same-store traffic turning positive after three quarters of declines despite lapping +3.0% growth. Same-store sales rose 3.7%, revenue grew 7% and margins expanded (ex-tariff refunds), while SG&A also leveraged. Importantly, higher price points are not driving customers away and should support basket growth, while materially easier H2 comparisons provide a tailwind to traffic. John views the recent margin confusion around tariff refunds as temporary noise rather than a change in the core thesis. With 5% unit growth, aggressive buybacks and improved unit economics, he remains a buyer following the post-results sell-off.
Communications
New Constructs remains firmly bearish despite the stock falling 35% YTD and ~80% since their original report. The core issue is that the fundamentals continue to move in the wrong direction relative to expectations embedded in the valuation. Daily active users are declining in SNAP’s key North American and European markets, while ARPU remains stagnant. At the same time, margins remain negative and cash burn substantial: SNAP has consumed $13.7bn of cumulative FCF (excluding acquisitions) since 2016, including $395m in 1H26. New Constructs argues the current valuation still assumes an implausibly large acceleration in users and monetisation and sees further downside, with their optimistic scenario valuing the shares at just $2.00 vs. $5.70 currently.
US rates: Has anything really changed?
Markets have gone too far in assuming no further Federal Reserve hikes, contends Jonathan Turek, warning that extrapolating recent softer spot data into the balance of risks is premature. The US economy remains biased towards hikes against a resilient backdrop where the unemployment rate is 4.1%, three-month average non-farm payrolls are adding 20k jobs, energy is above $80, and core PCE sits at 3.3%. Crucially, the $1T annual impulse from AI capex continues to push the cost of capital curve steeper, as bond supply from hyperscalers prevents forward rate cuts. With the FOMC seeking an excuse to hike, terminal pricing of just 35bps at the peak of the curve is far too low, underpricing the risk that the economy accelerates rather than slows in the second half. To capture both Fed terminal repricing and duration-led term premia, Jonathan is re-establishing a short in US rates and added a short in SFRH8 at 96.00.
Materials
GMR sees HBM as one of the strongest ways to play US copper growth, with Arizona emerging as the core of its long-term optionality. Copper World is approaching a sanction decision in late 2026, while the recently acquired Cactus project adds a second large-scale development opportunity and potential synergies. GMR estimates HBM could account for 30-35% of new US copper production by 2035, while projects across its broader portfolio are expected to increase total copper production by ~140kt over the period. The balance sheet has strengthened, 2027 production guidance implies ~30% Y/Y growth at the midpoint, and HBM trades at ~0.9x spot P/NPV10, a discount to Canadian peers. In a market short of copper equities, HBM offers growth optionality at a reasonable price and GMR would be surprised if peers have not noticed.
Taiwan: Firm inflation pressure
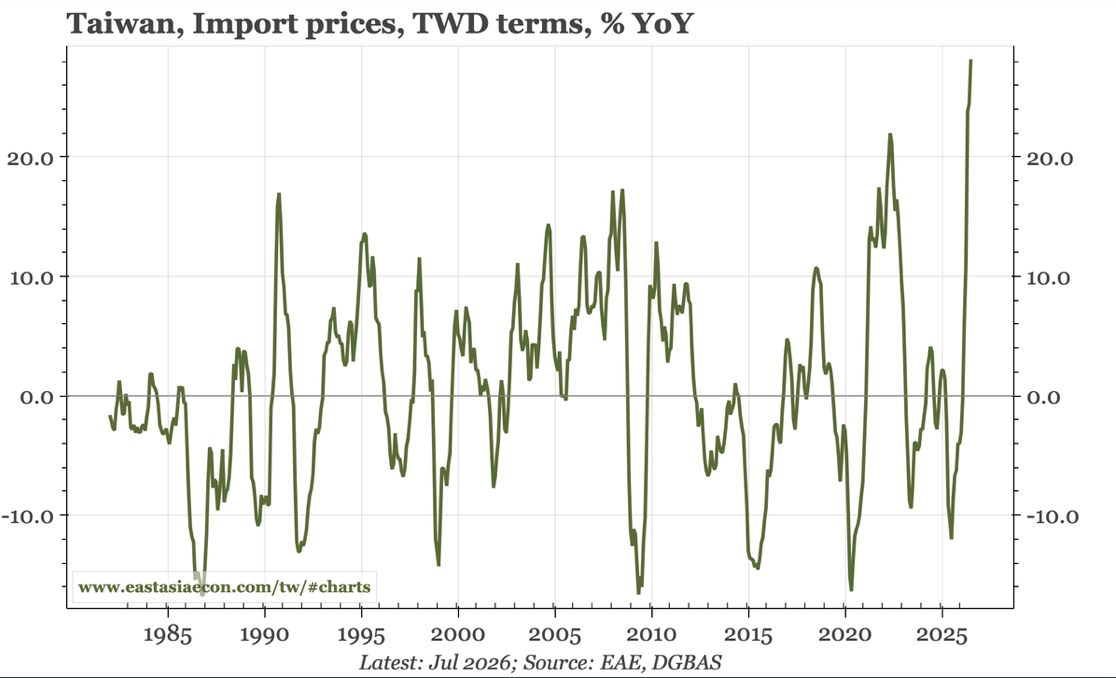
Although headline and core YoY inflation ticked down in July, Paul Cavey thinks overall inflation pressure in Taiwan remains firm. CPI excluding broad energy edged up to over 2% YoY, and despite price pressures easing elsewhere from the Iran War, the MoM annualised rate did not fall below 2%, which he feels is significant given core was closer to 1% last year. Pipeline pressures stay strong, with import price inflation accelerating to 25% YoY and PPI reaching 17%, the highest since the early 1980s. Paul suspects memory chip imports from Korea for AI accelerators are causing cost-push inflation, raising computer prices by 8.2% YoY. While export prices rose even faster to edge up terms of trade, Paul notes that private services inflation remains over 2.5% YoY.
Warsh invites the bond vigilantes
Manoj Pradhan points out that the 1:3 Z6Z7 steepener performed exceptionally well through the Federal Reserve, though Manoj did not anticipate Kevin Warsh would roll out the red carpet for bond vigilantes in his second meeting. Manoj argues that Warsh may get bailed out in the near term by President Trump’s desperation to find a truce ahead of midterms. However, if any truce holds and macro fundamentals once again start driving yields, he expects 100 basis points of hikes to eventually get priced into Z7 and Z8 because a massive procyclical fiscal impulse from the OBBBA will force the Fed to act if the economy overheats. Core inflation currently remains free of pass-through and there are no signs of overheating, but he believes growth remains very strong. Manoj advises that the 1:3 Z6Z7 steepener needs to be rebalanced to reflect President Trump’s truce announcement in conjunction with either 10-year or 30-year exposure.
Tech bubble implosion triggers shift to defensives
Michael Belkin is closing all short positions and initiating selective new buys across gold and silver equities as valuations reach major support zones. With silver down -51% from its January 29, 2026 peak, Michael views any further near-term weakness in precious metals as a buying opportunity. Meanwhile, the artificial intelligence bubble implosion is accelerating, causing corporate managers to mitigate damage as technology shares tumble. Big veteran institutional investors are orchestrating a major rotation into defensive sectors, mirroring the post-2000 tech bust where defensive sectors rallied while technology collapsed. Energy remains a core model long recommendation; Donald Trump’s tweets spoofing crude oil futures have bashed energy prices down, creating a buying opportunity. Michael recommends shorting tech and communication services while rotating longs into energy, health care, financials, staples, REITs, utilities, and gold and silver equities, alongside long XMAG/short MAGS and long IWD/short IWF ETF spreads.
Materials
Yuka Marosek sees DIC as an attractive opportunity after strong Q1 results challenged the market’s view of the company as a structurally declining printing-ink and pigment business. DIC is targeting record operating profit in FY26, above the prior FY17 peak, despite concerns over petrochemical-linked raw material costs. Yuka argues the mix is healthier than DIC’s legacy reputation suggests: packaging inks now account for nearly two-thirds of Packaging & Graphic sales, while the group is shifting towards higher-value “Chemtronics” electronic materials, including semiconductor epoxy resins, smartphone industrial tapes and specialty materials. Restructuring of pigments and legacy ink operations is also progressing, aided by activist investor Oasis Management’s 11.6% stake. With DIC still trading below book value, further margin expansion, earnings stability and capital-structure improvements from cross-shareholding and non-core asset sales should drive a re-rating.
Utilities
BEP’s Q2 results superficially support management’s message that cash flow can compound at 10%+, but the composition of growth is a concern. Gains on asset sales now represent c.66% of trailing 12-month FFO, the highest reliance Veritas has observed. Excluding those gains, underlying performance continues to deteriorate, with lower margins, weak generation and declining asset-level cash flow. Management describes asset-sale gains as recurring, but Veritas disagrees, arguing they depend on transaction volumes, buyer appetite, interest rates and market liquidity. They are lower quality than the contracted, inflation-indexed cash flows investors were told would drive growth. More concerning, capital recycling has recently extended into hydro assets at meaningful scale, despite BEP historically presenting hydro as a core competitive advantage. Veritas maintains a Sell rating and intrinsic value estimate of US$20.00 (40% downside).
Technology
Future has seen its share price recover recently having been unfairly hit by the “AIpocalypse” sell-off. The company works with management teams to design and build advanced, practical IT systems and is seeing larger orders come through. Near-term earnings are being held back by a major loss-making order, evident in Q1 operating profit growth of just 3% Y/Y to ¥3.4bn and expected to keep H1 growth similarly muted at c.3% to ¥7.3bn. However, Asymmetric expects earnings growth to reaccelerate from Q3 and into FY3/28, with the shares trading on c.12x FY3/28E earnings. Future’s work sits in upstream, mission-critical areas such as architecture, testing, validation, integration, performance design and systems responsibility, making AI more likely to improve productivity than displace the business. Meanwhile, its next-generation core banking system, Future Bank, also appears close to broader take-off.
Consumer Staples
Hedgeye has been short ELF for much of the past year, citing an oversaturated beauty market and soft organic core, with units down c.5% after the Aug 25 price increase, but now believes that last month's haircare launch creates a more constructive setup. They see haircare as a natural extension of ELF's dupe model into a fast-growing, high-priced beauty category, with $6-10 products undercutting prestige brands while “skinification” increases multi-SKU routine potential. The 2022 ELF SKIN launch, now the #11 mass skincare brand, provides a template, while the March haircare test sold out in 48 hours with 65% new-to-brand buyers. As the top line improves due to hair care launch, continued growth in Rhode/Skincare and international whitespace (legacy peers 70% Intl. vs ELF 20%) Hedgeye sees the stock revisiting $100 by year-end and more than doubling over a TAIL duration.
Communications
Richard Windsor argues that Meta’s failure to produce a AI leading model is playing to its advantage as it now can sell its compute capacity into the market for an excellent return. Bears see potential compute sales as evidence that Meta has overbuilt, that tokenmaxing is giving way to rationing and that AI compute demand may have peaked. Richard disagrees, arguing Meta is acting rationally while it gets its AI house in order, with its Muse Spark API delayed and its open-source lead ceded to Chinese competitors. The shortage argument is supported by Meta’s inability to buy more Google capacity, xAI’s recent high-return compute sales and data-centre supply constraints. He values Meta’s core business at c.$700/share, or $770/share including compute sales, implying 30%+ upside, and is considering taking a long position in the stock with a 9-to-12-month time horizon.
Canada inflation spike provides no cause for hikes
According to data in Screenshot 2026-06-25 at 12.47.26.png, Carl Weinberg observes that headline CPI-based inflation metrics printed higher than expected, if only by a squinch. Technically, headline CPI at 3.2% is pretty far above the 2% midpoint of the inflation target range. However, traditional core CPI was just 1.6% higher than last year, while the Bank’s preferred measures of core inflation, CPI-median and CPI-trim, averaged just 2.05% between them. Sticking to his guns, Carl notes that the BoC did not raise rates at its last meeting because it didn’t have to. Petrol prices were behind the acceleration of headline CPI, but there is little sign those cost increases are bleeding through into core prices. The economy has plenty of slack to absorb the energy price increases, unlike the US where output is camped at the edge of the production possibility frontier. This result gives the BoC no cause to contemplate rate hikes now.
AIDC liquid cooling enters a scaling cycle
Industrials
Liquid cooling is moving from an efficiency upgrade to a functional requirement for high-power AI data-centre racks. The cleaner domestic China exposure is not necessarily the system-level liquid-cooling vendors, many of which have limited direct exposure to NVIDIA's core ecosystem. Instead, Horizon Insights sees more visible order conversion in the precision-machining equipment used to produce liquid-cooling quick-disconnect connectors. UQD/QD connector expansion is driving demand for Swiss-type lathes, where Tsugami China appears to have c.60% share in China’s connector-processing equipment market. Channel checks also point to >2,700 liquid-cooling-related orders in Jan-May 26 and potential 2026 shipments of c.6,000 units, implying c.RMB2.7bn of potential revenue at c.RMB450k per machine.
Bear’s Den Idea Forum
Despite the market hitting all-time highs amid rapid sector rotation and narrow breadth, Bear’s Den remains one of MYST’s best-performing Forums - their previous event (March) produced an impressive ~83% positive hit rate with a record average alpha of ~19%. Stocks featured at their June Forum included:
CoreWeave (CRWV US) - Vendor-financed neo-cloud faces real bankruptcy risk. TP $50 (50% downside).
Ingredion (INGR US) - Secular short with high leverage + negative volume trends. TP $65 (35% downside).
Logitech (LOGI US) - AI-driven headcount cuts to negatively impact demand for core Peripherals business. TP $75 (25% downside).
McDonald’s (MCD US) - Convenience moat deteriorating as drive-thru share collapses. TP $199 (25% downside).
US Cable / Telcos (incl. AT&T, T-Mobile, Verizon) - Fibre to flip from asset to liability as Starlink + Amazon satellite buildout expands.
Japan: Yen under pressure, but data is encouraging
Graham Turner says that the prospect of a rate hike at the FOMC meeting in June casts a harsh spotlight on the Bank of Japan: the BoJ will meet earlier next week, and unless it agrees to tighten policy too, the yen is likely to plumb new lows against the US$. For the Bank of Japan, there is no obvious pressure to hike, as inflation has been well-behaved. The y/y for the Nationwide CPI eased to 1.38% in April. The CPI excluding food, alcohol & energy dipped to 1.06% y/y. Real wages are rising sharply, in part, because of the drop of core inflation as well as fuel subsidies. The labour market in Japan is tight. The unemployment rate fell to 2.5% in April. Total employment jumped to 68.76m, a new high, despite a shrinking population. These are encouraging trends that bode well for Japan’s response to an ageing population, particularly against the backdrop of high government debt.
US: The populist backlash against AI
Matt Gertken and Marko Papic say that the populist backlash against AI could result in bipartisan regulation in 2027, but is especially likely to prompt tax hikes from 2029. Public criticism of the new technology is growing and politicians in the US and abroad are proposing measures such as AI regulation, taxation, redistribution, and restrictions on data centres. Job displacement is the core concern, with opposition to AI strongest in service-oriented economies where workers fear automation. Americans increasingly view AI as developing too quickly, oppose data-centre construction in their backyard, and are becoming less optimistic about the benefits of technology, particularly among younger generations. The investment risk is political, not technological: a recession, AI-driven mass layoffs, inflation, or a major AI-related accident could mobilise voters and lead to aggressive regulation or higher taxes on technology firms as early as next year – and especially after the 2028 election.
Stock Picking: #1 ranking for 60 straight months
New Constructs highlights a milestone 60 consecutive months of #1 rankings across multiple SumZero categories, underlining the consistency of their stock selection record. They are currently top in Consumer Discretionary and Industrials, alongside strong showings in Value, Large Cap, Micro Cap and Healthcare. New Constructs attributes this track record to their proprietary Robo-Analyst AI, which analyses financial statement footnotes and MD&A disclosures to calculate Core Earnings, a proven superior measure of earnings. Their performance evidence also extends beyond the rankings: since Jan 2021, New Constructs’ Focus List Long portfolio has outperformed the S&P 500 by 20%, while their Short portfolio has outperformed shorting the index by 60%. The three indices that they have developed with Bloomberg’s Index Licensing Group have also all outperformed the S&P 500 over the past five years.
Korea: Everything but a hike
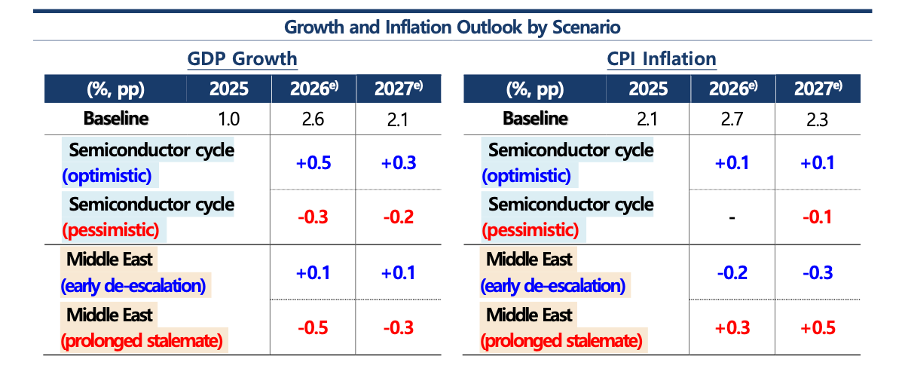
The BOK didn't hike today, but reading through the materials, Paul Cavey comments that it was a surprise that it stayed on hold. The governor made it clear that rate hikes were coming. Three aspects of the forecast stand out for markets. The BOK now thinks the current account surplus will be $250bn in 2026, up from a $72bn forecast just months ago. The bank also thinks core inflation will be 2.4% in 2026. That feels low, given core was at 2% before either of the shocks from Iran and semiconductors, and with the BOK itself flagging that big tech profits will lift nominal wages. If the semiconductor cycle and the Middle East situation were to evolve simultaneously in the pessimistic direction (see chart), adverse feedback loops between financial conditions and the real economy would emerge, further amplifying the growth slowdown.
US: Warsh’s natural bias
In the last week markets have moved to peg the Fed for about 28bps of hikes in the next year, a substantial shift from the 1-2 cuts priced in late February. Warsh assumes the Chair with a challenge to his natural bias – higher productivity via AI implying stronger GDP growth potential (but less inflation and hence need to hike), weak jobs markets but immigration arguably keeping the U/E rate down (which should point to rate cuts), a tighter and smaller Fed balance sheet (that implies rate cuts to offset) and different measures of inflation (trimmed mean over core PCE which conveniently is lower and implies rate cuts). This set of biases imples that Warsh is more of a cutter than a hiker. While the markets peg the first Fed hike in March 2027, Craig Ferguson thinks that the Fed will get an inflation shock in the next 3-4 months that leads to them hiking in Q3.
Technology
CORZ moves sharply higher in Arete’s AI infrastructure rankings following a major expansion in its long-term power roadmap, with them now modelling 3.6GW of IT load and $6.3bn of NOI by 2032 - up from prior estimates of 1.9GW and $3.7bn, respectively. Arete argues demand for AI compute remains “off-the-charts”, while CORZ is becoming increasingly attractive to hyperscalers through the expansion of its Pecos and Muskogee campuses into gigawatt-scale AI data centre sites. Importantly, the company has leveraged its existing CoreWeave contract into $3.3bn of financing, giving it sufficient capital to begin pre-building new facilities before signing additional leases, which Arete views as a key competitive advantage. With leasable power expected to nearly triple over the next few years, Arete raises their TP to $55 (100% upside) and now ranks CORZ alongside Applied Digital as a top pick in colocation infrastructure.
Industrials
Hamed Khorsand’s bearish call on KRMN is already playing out with the shares down ~40% since his Sell initiation earlier this year, yet he continues to see material downside with a 12-month target price of $37. Acquisitions masked underlying weakness in the company’s core business during Q1. Excluding newly acquired maritime defence assets, revenue would have declined sequentially, despite a strong defence spending environment. Hamed also flags KRMN’s rising contract assets (unbilled receivables), which now exceed 32% of the company’s 12-month trailing revenue, alongside weak FCF generation. Valuation remains elevated at ~42x EV/EBITDA, while comps begin to look tougher as the year progresses.
Materials
APAM is evolving from a cyclical European stainless-steel producer into a more diversified materials platform, supported by its integrated recycling activities and higher-value product mix, which VRS believes should improve long-term margin resilience and sustainability alignment. Recent performance reflects a challenging market backdrop rather than a deterioration in core fundamentals, with VRS highlighting operational efficiency improvements, the strategic importance of ELG recycling and the acquisition of Universal Stainless, which expands APAM’s aerospace footprint in the US. Europe’s increasingly protective stance on steel imports could also add ~€200m to EBITDA from 2027 onwards while improving utilisation rates. Their analysis incorporates a valuation framework combining six different methodologies spanning intrinsic, peer-based and probabilistic approaches.
Roche - SERD: Is lidERA being over-extrapolated?
Healthcare
Foveal published on adjuvant SERDS and sees a mispricing emerging between Roche and AstraZeneca, with the market potentially extrapolating lidERA into a broader commercial opportunity than is warranted, while underappreciating a more practice-aligned pathway elsewhere. The core debate is whether investors should be underwriting a broad SERD backbone in early breast cancer today, or positioning for a narrower outcome with a different catalyst path into 2027 that could shift relative value across the group.
Communications
CEO Johan Svanstrom is the wrong leader for RMV’s critical transformation. Despite bringing a background as a “digital native” who scaled Expedia’s Hotels.com to over $3bn in revenue, more recent roles at BIMobject and RMV reveal a polarising leader who is disinterested in operational details and relies on a closed circle of advisors. Svanstrom will continue to champion an AI strategy with high-level, buzzword-driven directives while delegating core business oversight, creating significant execution risk and key-person dependency on a team he has already begun to alienate. His chaotic leadership and lack of operational discipline are a direct mismatch for the rigorous execution and financial control the company desperately needs. Paragon’s research includes interviews with former senior executives who worked with Svanstrom for more than 32 years combined.
Consumer Discretionary
Stellantis’ latest results reinforce concerns that its finance arm is masking weakness in the core car business. While the market is focused on the potential for a recovery in earnings, the report argues that rapid growth in leased vehicles and heavy use of off-balance-sheet JVs is helping support sales and industrial free cash flow. With credit ratings now close to junk, higher funding costs could undermine this support and create further pressure.
Consumer Discretionary
Lululemon shares are trading at both 52-week and five-year lows after a difficult period marked by product challenges and pressure on the brand’s core offering. The source notes that the company had strayed too far from its brand DNA, with limited colour in parts of the range and the departure of its senior merchant. However, early signs of improvement are emerging, including a tighter product offering, more colour and the appointment of a former Nike executive as CEO. While a full turnaround is likely to take time, The Retail Tracker sees potential for the stock to reach $175 over the next 12 months.
Consumer Discretionary
Paragon’s executive diligence memo was originally published when Heidi O’Neill was being discussed as a potential CEO successor at Nike and they viewed her as a poor fit for that role. At LULU, she is somewhat better matched to the brief, but their core reservations remain. She has tended to look stronger as an operator and internal brand steward than as a true strategic architect. That matters at LULU, where the challenge requires a sharper product vision, stronger innovation instincts and a willingness to make harder calls on strategy and talent. So, while the fit is better than it would have been at NKE, Paragon still views her as more of a stabiliser than an obvious answer to LULU’s deeper issues.
US: Underlying inflation trends are cooling
Report by
Ironsides Macroeconomics
Barry Knapp argues that recent geopolitical shocks—particularly the Iran conflict—have not meaningfully altered the medium term economic or inflation outlook. By focusing on stated policy objectives rather than speculative geopolitical outcomes, Barry concludes that escalation risk remains limited and that markets largely share this view. Inflation expectations normalised quickly, equity markets avoided a sustained dislocation and the anticipated “fat pitch” equity market overreaction never materialised. Inflation remains the central macro issue, but underlying trends are cooling. March CPI was elevated due to an energy price spike, yet the key components - core goods, rent of shelter, and non housing services - continue to moderate. Barry stresses that post pandemic seasonal adjustment distortions are overstating inflation pressure and risk repeating policy mistakes made after the Global Financial Crisis. He views the Fed’s rigid 2% inflation target as poorly conceived and expects trend inflation to settle nearer 2.5% over time.
US: The AI boom continues
Graham Turner comments that there is plenty of inflation stuck in the pipeline despite some respite for energy prices. The headline CPI was up 0.87% m/m in March but the core CPI was well behaved. The key will be broader, second-round effects from the higher headline numbers. That will depend on consumer resistance: slower wage growth and uncertainty over job prospects due to AI could limit the ability of companies to push prices up more generally. The oil price shock has not yet had much impact on services demand, if the non-manufacturing ISM is any guide. The new orders index rose in March to its highest level since February 2023. There could be a delayed reaction to the Iran conflict, but Graham sees this as a potential sign that the US economy is indeed quite resilient. Low core inflation and no clear evidence that the energy shock or AI are damaging the economy would represent a big buying opportunity for equity investors.
Industrials
Grid constraints threaten to slow data centre construction growth, potentially disrupting STRL’s key revenue growth and margin expansion engine. Early signs are already visible, with decelerating construction data, softer backlog and margin pressure in its core E-Infrastructure segment. The CEC acquisition is a desperate move by management to mask a plateau in its site prep business and expand into Texas ahead of increasing competition. With cash flow moderating (and diverging meaningfully from adjusted earnings), insider selling rising and valuation elevated (~22x EV/EBITDA), OWS is targeting more than 30% downside.
OpenClaw drives AI shift, but disruption risk overstated
Communications
Report by
Blue Lotus Research
Blue Lotus argues the rise of OpenClaw and AI agents is reshaping China’s internet ecosystem but believes market concerns are overstated. While agent frameworks could emerge as new traffic gateways and LLM platforms have already captured 8-10ppt of global traffic share, they see disruption as more incremental than structural in core consumer use cases. China’s low software penetration supports rapid AI adoption but also limits near-term cannibalisation. Despite execution premiums being assigned to startups and ByteDance, Blue Lotus believes incumbents such as Tencent and Alibaba retain strong underlying advantages and sufficient time to adapt. Recent share price weakness is therefore seen as a buying opportunity. However, they turn more cautious on Kuaishou, removing it from their Top Buy list amid intensifying competitive pressures.
US Producer Price Index
For the January PPI report, John Ryding wrote the report "ought to be a blow to hopes of a quick return to 2% and further suggests that monetary policy is accommodative". The report for February adds to this assessment ahead of the oil shock adding to price pressures. Final demand PPI inflation rose to 3.4% from 2.9% on a 12-month basis with all major categories adding to the upward pressure (core goods, food, energy, and services--see table for details). On the old methodology basis for goods, the pipeline pressures were rising strongly even before the oil price shock. Not only is it too soon to say that PPI inflation is moving in a way that it is consistent with a gradual return to 2%, but it is also too soon to say if the upward move in inflation is levelling off.
Consumer Discretionary
The Retail Tracker sees improving momentum at AEO, driven by a rebound in Aerie, which returned to growth in late 2025 following assortment resets and a renewed focus on its younger customer. They expect this momentum to continue, supported by a positive contribution from Offline despite some lingering assortment inconsistency. By contrast, the core Eagle brand remains mixed: denim is "solid" with exposure to emerging trends such as ripped jeans and bootcut styles, but tops lack impact (the online range is much better than in store). Increased marketing spend - including partnerships with high-profile celebrities and country music events - is driving traffic and sales. With the stock down ~30% amid recent market volatility, AEO is an attractive opportunity at current levels.
Consumer Staples
Scott Mushkin remains cautious on TGT despite management acknowledging some operational challenges flagged in his field research. Recent store visits continue to reveal poor endcap execution, high levels of discarded items, long checkout lines, out-of-stocks and even extreme messiness. These nagging store operating challenges are likely to take more effort to overcome than management currently believes. He also sees several structural pressures ahead. TGT may need to sacrifice gross margin to improve price competitiveness, while everyday essentials could face deflation in 2026 amid heightened competition. Meanwhile, Walmart and Amazon are unlikely to cede share and TGT’s core demographic offers limited growth. Scott believes the recent swing to positive sales reflects easy comps and short-term consumer spending variability rather than a structural improvement in demand.
Why (some) EM Telcos’ multiples could double
Communications
The resumption of pricing power is one of the key drivers of the rally in EM Telcos and perhaps the area where consensus is most sceptical. In this note New Street analyses which markets have the greatest potential for sustained pricing power, looking at key issues: affordability and regulatory and competitive structure. Where these come together they see the potential for a multi-year period of above-inflation revenue growth from the core telco business. They also show that where pricing power is sustained, EM Telco multiples have doubled. As this plays out across the industry the scope for above market returns are high, and New Street remains (very) bullish on EM Telcos.