No matches for this search
Try adjusting your filters or search criteria
Western miners: Copper multiples driving value creation
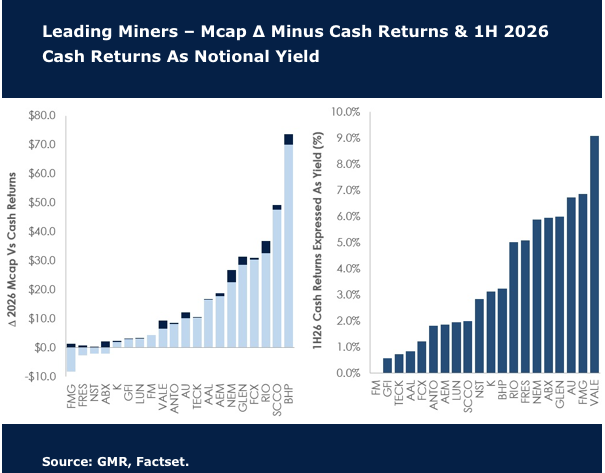
The leading 20 western miners added roughly US$330bn in market capitalisation in 2026, delivering an average share price return of 22%, though David Radclyffe argues performance remains strictly a stock-picker's market driven by divergent commodity forces. BHP Group Ltd and Glencore PLC jumped some 48%, whilst Fortescue Ltd dropped 15% alongside softer iron ore. David explains that expanding base metals multiples—predominantly copper, up ~15%—more than offset weaker bulk commodities. Meanwhile, the gold sector has caught the buyback bug that diversified miners abandoned post-2023 in favour of growth. Cash returns across the peer group totalled merely ~9% of net value creation, demonstrating that cash payouts matter far less than market forces and multiple expansion during volatile cyclical upturns. Though backward-looking yields make iron ore miners appear optically cheapest, markets look forward; cash returns equate to far less of total returns than investors think over short timeframes.
Overlooked opportunities in YWR’s QARV rankings
Why do China, shipping, iron ore, hardware, Brazil… all stand out if you screen high ROE’s with low valuation? Erik@YWR sees it as scepticism about global growth on which he is taking a contrarian view. Following this month’s review of YWR’s QARV rankings key themes include: 1) A massive China bull market has only just begun. 2) Opportunities in iron ore, where Fortescue, Rio Tinto and Kumba are delivering ~20% ROEs at <12x P/E despite China’s property crash. 3) The Taiwanese semiconductor supply chain stands out as highly profitable and undervalued. Everyone focuses on Nvidia and the datacentre buildout but misses the whole Taiwanese supply chain behind this. Tokyo Electron and ASML also screen well. 4) Brazil is overlooked, with names like Itau, Vale, Ambev and B3 all screening well. 5) Container shipping - supply-chain diversification could sustain tighter freight rates than investors expect.
Iron ore: Falling prices pausing, or the cycle restarting?
Iron ore prices recently bounced off US$100/t, raising the question whether this represents a pause in the correction, or perhaps early signals that the price cycle is restarting. Sentiment continues to focus on broad demand risks especially in China, nevertheless Chinese crude steel production continues to annualise at +1Bt/yr, with the rest of the world’s demand recovering. David Radclyffe believes investors are getting close to an opportunity to start accumulating iron ore stocks; iron ore producers trade on a prospective 2023 FCF and dividend yield of 9% and 8% respectively. David’s preferred exposures are Vale, Fortescue Metals Group
and Labrador Iron Ore.
Investment opportunities in iron ore despite uncertainty
Despite uncertain Chinese growth rates and hence iron ore demand, along with rising inflation and the Russo-Ukrainian war, David Radclyffe believes there may be more time to stay invested in the iron ore sector. With FCF yields remaining high for pure plays and diversifieds (~14%), investors should look for strong dividend yields (~9%) and cash returns this year. The big global diversifieds continue to offer better value than the pure plays, with Vale the preferred single entry, followed by Rio Tinto. For pure plays, David’s preferred exposure is Fortescue Metals Group, a non-consensus call.
Materials
Always worth another look when the market is so bearish - the stock currently has no analyst Buy ratings. To GMR the underlying numbers (1.1x P/NPV or 0.4x @ spot; 10% dividend; 11% gearing) and the iron ore market outlook represent an enticing opportunity. Over FY23-FY24 GMR’s base case has a cash surplus for FMG of US$2.4bn post FFI (US$1.2bn) and dividends (US$8.8bn). China crude steel rebounded in recent months to ~1Bt/yr, supply remains constrained and demand solid. Product discounts troughed in late 2021. Yet there is a ~US$30/t arbitrage of the 2022 futures to consensus.
Materials
Pass-the-parcel - you can only give so much away before there’s little left to unwrap. Divesting the Petroleum business leaves BHP with little to differentiate it from Rio Tinto and Vale. BHP should have used its petroleum expertise and customer base to build a hydrogen / ammonia business taking a leaf from Fortescue’s playbook. From a ROCE and CO2-e perspective the met coal business would have a greater overall impact on the business if it were divested. However, the problem appears to be a lack of interested buyers.