ROADSHOWS: Communications / Media / Software - Andrew Freedman & Felix Wang /Hedgeye   •   London 10 - 11 Nov   03 - 11 Nov 26       Behavioural Finance, Portfolio Strategy & Quant - Jim Rocchio /Kailash Capital Research   •   London   05 - 05 Nov 26       US, European and Asian SELL / SHORT Ideas - Robert Prather /Vision Research   •     10 Nov - 15 Dec 26      
Filters

The Cut

Fortnightly publication highlighting latest insights from IRF providers

Company Research

Materials

Report by Global Mining Research

Just three months after GMR warned that NST looked vulnerable to a takeover, Gold Fields has made an unsolicited A$27/share bid at a 22% premium. They identified GFI as one of the more logical strategic buyers, and the combination scores highly on GMR’s M&A rationale framework given the asset overlap, potential synergies, combined production of 4-5Moz/year and greater Australian weighting for GFI. NST has rejected the proposal as opportunistic, but at just 0.58x spot P/NPV5 it remains one of the cheaper large-cap gold names despite producing more than 1.5Moz annually and owning high-quality assets. GMR now asks whether this is simply the opening salvo, while pressure will be on the new CEO to deliver KCGM and show value within the portfolio.
Edition 246 - 02 Oct 26

Returns on capital: Copper vs Gold

Report by Global Mining Research

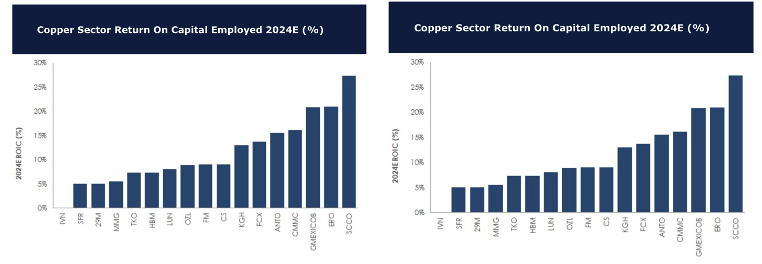
For 2024, David Radclyffe forecasts copper to enjoy an average ROCE of 11.1%. The standout is Southern Copper Corp, helped by some very low cost and long-lived assets. Relatively new to the market Ero Copper Corp does well, while at the lower end sit Ivanhoe Mines and Sandfire Resources. When it comes to gold, the forecasted average ROCE for 2024 is at 8.3%, with Gold Fields coming out on top and Lundin Gold close behind. The copper sector as a whole continues to generate better real returns on capital than the gold sector, with gold miners continuing to suffer from shorter mine lives and a commitment to M&A to create growth.

Edition 155 - 03 Mar 23