Consumer Staples
BID remains an attractive way to play the structurally resilient shift towards eating out of home, with scaled distributors capturing more of the economics than restaurant operators themselves. Foodservice demand has compounded through the financial crisis, Covid, inflation, delivery apps and GLP-1 adoption, while barriers to entry in broadline distribution remain high because of route density, cold-chain infrastructure, purchasing scale and technology. BID combines that structural backdrop with record FY26 trading margins, light gearing, strong cash generation and a proven bolt-on acquisition model. Europe remains the main profit engine, while the UK offers the largest margin upside. Despite this, the company trades at just 16.5x FY26 P/E vs. materially higher US peer multiples.
Indonesia: Good companies at bargain prices
The substantial de-rating of some of Indonesia’s best businesses, alongside low inflation and a depressed real effective exchange rate, has created a rare opportunity to buy market leadership, strong management and growth at attractive valuations. David Scott’s top picks are Bank Central Asia, Cisarua Mountain Dairy, Multi Bintang Indonesia, Sumber Alfaria Trijaya and Kalbe Farma. BBCA combines strong organic growth in an underbanked economy with improving efficiency and now trades at just 10.7x P/E. CMRY offers strong dairy and packaged-food brands, direct distribution and 30%+ ROE, while MLBI combines the iconic Bintang franchise with pricing power and high cash generation. AMRT’s dense Alfamart network and procurement scale underpin further store and online growth, while KLBF offers diversified healthcare exposure, broad distribution and established local brands.
Technology
Taiwan's ban on China-made glass fiber yarn keeps Taiwan laminate plants buying E-Glass locally through at least 2028, and JNK's research indicates Nan Ya Plastics Corp, the largest local supplier, holds the pricing power. The laminate makers behind high-end AI boards, including Elite Material Co Ltd, have asked for an exemption, but JNK sees one as unlikely while Nanya is still adding capacity. JNK estimates Taiwan's E-Glass shortfall could approach half of demand in 2027 as local glass makers shift lines to Low-Dk fiber. The main risk is AI server customers moving laminate volume offshore as the cost gap widens.
Consumer Discretionary
Alibaba Group Holding Ltd is pivoting from acquisition-led expansion to disposals and artificial intelligence, redirecting capital toward AI infrastructure and cloud whilst streamlining non-core assets. VRS highlights that external Cloud Intelligence revenue expanded 40% Y/Y in the March 2026 quarter, yet heavy investment is depressing near-term economics: FY26 adjusted EBITA dropped 56% to RMB76.4bn as free cash flow reversed to an outflow of RMB46.6bn following the group’s commitment to invest at least RMB380bn in AI and cloud infrastructure over three years. Meanwhile, domestic marketplaces have lost share to PDD Holdings Inc and Douyin, driving heavy quick-commerce spend. Valuation multiples have compressed markedly, with the shares trading at 14.87x P/E and 10.43x EV/EBITDA on 2025 figures against an asset base carrying negative net debt of USD10.06bn. VRS sets a weighted target price of USD150.56 (37.20% upside) by blending a two-stage DCF valuation of USD132.61 (60% weight; 20.84% upside) with a peer group valuation of USD177.49 (40% weight; 61.73% upside).
Consumer Discretionary
Management was clear that market conditions have deteriorated over the past 3 months, with higher interest rates, inflation, gas prices, and tougher housing affordability. Yet Lennar Corp persists with increasing incentives and sacrificing margins to maintain even-flow production. This strategy risks slow-motion financial “suicide”, as there is no natural bottom to margin degradation when chasing demand at affordability. This pressure stems from their land bank structure; unable to renegotiate take-down pace, Lennar must buy lots and burn inventory or incur higher option fees. FY26 EPS is forecast at USD4.80/share (down from USD5.47/share), with FY27 lowered to USD4.54/share (down from USD6.38/share) as margins compress under 7% interest rates. LEN trades at 16.3x FY26 P/E vs 16.1x for peers, and 1.04x adjusted tangible book value vs 1.35x for the group. Fair value estimate is USD68/share vs GAAP book value of USD91/share.
Are US stocks cheap?
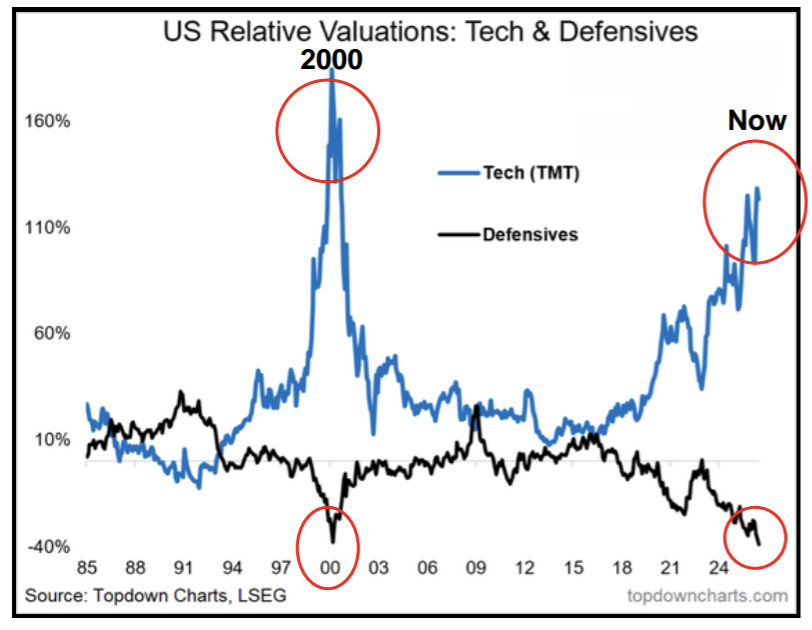
The S&P 500 has pushed to all-time-highs through a pandemic, tariffs, the Iran war, and a 10-year Treasury yield spiking near 5.3%. Through it all, earnings have done the heavy lifting. Forward earnings growth near 40% is at a level investors have rarely seen. This year, earnings growth added more than 27 points to the S&P 500’s return, while a shrinking P/E took away more than 15. Even as the S&P hits record highs, the forward P/E of the index has fallen to 19, below its 5-year average. Tech, the market’s biggest sector, drove much of this drop. It went from the most expensive sector at 30.7x to below 22.5x in a year, as its earnings outran prices. Meanwhile, the 10-year yield is up ~475 bps from its lows, and it now pays about as much as the S&P 500’s earnings yield. If yields roll over, stocks at these levels look compelling. However, Francois Trahan says if yields keep climbing, earnings will have to continue carrying the market alone.
Top 20 UK SMID stocks
Their Systematic Analysis Model (SAM) ranks 290 UK stocks by combining revisions momentum, shareholder value and valuation to identify the most attractive opportunities. Hikma Pharmaceuticals and SigmaRoc are the latest additions to their top 20 ideas. HIK screens as unusually cheap for its quality, ranking in the top quintile on capital-returns valuation and trading at just under 8.5x FY2 P/E. ROCE has been improving since 2022, revisions momentum has strengthened for 8 months and is back above median, while a new CFO and strategic reset provide meaningful recovery potential. SRC has seen ROCE grind higher with OPAT margins increasing materially following the successful integration of CRH assets. It is still very cheap with the market implying it can only do 6% ROCE with the FY2 forecast at 8%. Revisions Momentum is back above median and improved significantly over the past 3 months. There is also scope for further M&A. TPs are 1900p for HIK and 216p for SRC.
Energy
Priced for shrinking margins just as pressure-pumping capacity is tightening. North American frack calendars are already filling, pricing power is improving and record-low inventories of drilled-but-uncompleted wells mean producers increasingly need new drilling rather than simply completing old wells. International growth provides a second leg, with HAL targeting ~$16bn of revenue by 2028. Recent awards in Brazil and Saudi Arabia add further upside, while Kailash sees potentially substantial future revenue and profits from Venezuela, where HAL could be one of the biggest “picks and shovels” beneficiaries if the recently announced US oil deal progresses. FCF remains strong and has funded meaningful buybacks. Despite this improving backdrop, the stock trades at just 15.3x 2026E P/E and 8.5x EV/EBITDA, large discounts to SLB, Baker Hughes and the broader market.
Consumer Staples
John Zolidis argues SFM is still misunderstood by the market, which continues to treat it like a conventional grocer. Instead, he sees the company as a high-ROIC compounder, with its differentiated assortment and focus on health-conscious consumers supporting stronger structural margins, better inventory turns and higher FCF than typical food retailers, while that customer base should also grow faster than the broader population. At just 12 P/E and 7x EV/EBITDA, the shares are trading at discounts to historical averages and cheap multiples on an absolute basis. In a return matrix John estimates one-year upside potential of 50% with a 10x EV/ EBITDA multiple vs. 15% downside using a 6x multiple. He would take advantage of recent weakness to add to or establish new positions in SFM.
Consumer Discretionary
Iii’s channel work raises questions over whether Meesho’s improving reported unit economics are as durable as management suggests. Experienced e-commerce operators argue that logistics efficiency, rather than advertising, is the key determinant of marketplace profitability. While management reported another sequential decline in logistics cost per delivered order in 1Q27 despite higher fuel and wage costs, Iii’s channel work suggests defect rates remain above industry benchmarks, potentially offsetting those savings through higher return-handling and refund costs. With roughly two-thirds of GMV-contributing sellers already advertising, further ad growth increasingly depends on pricing and inventory mix, making Meesho Mall important to the next leg of monetisation. Iii sees logistics cost per delivered order as the key test: another decline would support management’s case, while a flat or rising print would strengthen the sceptical channel view.
SaaSpocalypse dying
Technology
Another excellent performance from Snowflake in Q2 hammers a further nail into the coffin of the SaaSpocalypse theme that had taken the sector down sharply. Richard Windsor sees the results as further evidence that enterprises will continue to need software and are increasingly turning to existing vendors to help deploy AI in a safe and controlled way - a positive read-through for Salesforce, SAP, ServiceNow and Adobe. He is less enthusiastic on SNOW itself, however, given a valuation of more than 150x FY27 P/E. Richard sees better value elsewhere and owns NOW and ADBE, which remain only around 25% of the way to his target prices.
UK strategy insights
Trendrating’s latest analysis provides data-driven insights into the combinations of fundamental parameters that have historically generated the most alpha in UK equities. They have ranked the factor combinations most rewarded by the market across one-, three- and ten-year periods, providing investors with a factual framework for factor-based decision-making. Over the past year, the strongest-performing combination has been Lowest P/E and Highest 3-Month Sales Growth, delivering a 37.2% return and outperforming the benchmark by 17.7%. Lowest P/E combined with Highest 12-Month Sales Growth ranked second, returning 33.4%, while Highest 3-Month Earnings Growth alongside Highest 3-Month Sales Growth returned 32.5%. Top 3-Month Earnings Growth combined with Lowest P/E was the weakest performer. Click here to access the full ranking list.
Industrials
AlphaValue raises their FY26 estimates on better H2 visibility, stronger automation penetration and an improving margin mix. The order backlog is up 23% Y/Y, while a greater contribution from smaller, higher-margin orders should offset the heavier weighting of lower-margin key-account projects seen in H1. FY27 sales and EBIT estimates rise 3%, with FY28 forecasts increased 5%. AlphaValue expects continued growth in warehouse automation to increasingly offset weakness in ITS, supported by long-term structural drivers including labour shortages, the continued expansion of e-commerce and the growing importance of reverse logistics. While competition from Asia, particularly Chinese players, remains a drag, AlphaValue believes the expanding secondary market for lithium-ion battery-powered trucks should remain supportive and become increasingly relevant over the coming years. TP €35 (45% upside).
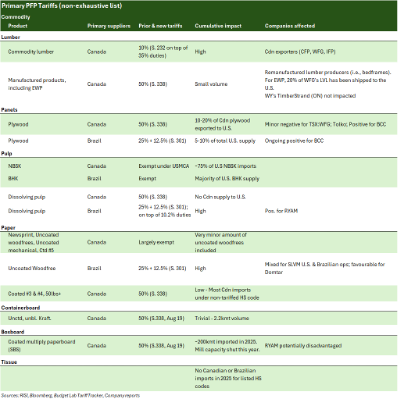
Limited impact of US tariffs on wood producers
The series of new US tariff announcements include 50% tariffs on ~5% imports from Canada, a 25% tariff on Brazilian imports and 10–12.5% tariffs on virtually all trading partners. The new tariff suites apply to more categories, with the latest possible impact on Canadian exports appearing to be in paperboard and plywood. Although plywood will see some direct impacts (table), public companies in Canada have little exposure. US plywood producers should benefit from lower Brazilian uncoated woodfree imports, although the team expect incremental impact on the names in their coverage universe. Given the inflationary impact on freight/personal transportation from the Iran war, persistently high rates, and escalating domestic energy costs, the team are cautious on the housing market outlook and underlying consumer demand. They see limited benefit to US producers from these latest tariff machinations, with some producers benefiting from one category but hurt by another (e.g., Sylvamo Corp, Rayonier Advanced Materials Inc).
Healthcare
At 30x forward adjusted EPS, DXCM continues to raise multiple earnings-quality concerns, especially when compared to Insulet, which has cleaner accounting and trades on a lower P/E. Insulet’s rebates and sales incentives are 25 days of sales, while DXCM’s have exceeded 100 days in seven of the past eight quarters and continue to reach new highs. Inventory is also rising despite heavier discounting, with finished goods having tripled. Price discounts should reduce inventory value through a higher reserve, but reserve growth has stalled, supporting EPS. Warranty accruals also look low, while flat dollar R&D spend in Q1 added 3c to EPS as a percentage of sales. Other companies reporting next week where BTN has recently flagged earnings-quality risks include Belden, Church & Dwight and Eaton.
Utilities
MTLN’s Asset Rotation Plan and its impact on cash flow remains poorly understood by the market. Renewable-project SPV sales are treated as revenue-generating contracts rather than disposals, allowing MTLN to recognise “catch-up” revenue once a sale is signed, based on management’s estimate of project completion. Contract assets linked to the plan rose from €0.92bn to €1.41bn in 2025, increasing the risk of later write-downs if assumptions prove optimistic. Forensic Alpha also identifies asymmetric cash-flow treatment: development spending can be classified as capex when projects sit in PP&E, while subsequent sale proceeds may enter OCF after reclassification to inventory. Together with similar treatment of CO₂ allowances, they estimate c.€338m of benefit to reported OCF. MTLN is less cash generative than appreciated, leaving liquidity, leverage and refinancing more exposed if project sales slow.
Are E(U) ready?
Examining the Ankara summit, Niall Ferguson delineates an alliance defined by greater European self-sufficiency in conventional deterrence and reduced American forces on the Continent. Niall considers Europe's conventional capabilities sufficient to deter Russia, but warns that the rift in the transatlantic alliance leaves vast capability and logistical gaps to fill before Europe becomes conventionally defensible by 2030. He identifies Washington's plans to reduce force commitments as the most consequential development within NATO, creating an operational window that a recovering Russia could exploit to expose the dwindling credibility of Article 5. For Niall, Europe's greatest vulnerability is the US reduction in logistics rather than combat aircraft, as a shortage of air-to-air refuelling and strategic airlift yields a substantially thinner margin of security. While he places low odds on a conventional Russian attack, Niall foresees Moscow continuing hybrid and covert operations below the politically contested Article 5 threshold.
Industrials
An under-covered EPCO-linked electrical engineer, Toenec is now the cheapest among its peers, trading on <12x P/E with a 3.4% dividend yield. Asymmetric argues margins should continue to benefit as higher-margin private projects increase while pricing on EPCO work also improves. They see substantial order potential in Japan's industrial heartland of Chubu, driven by enterprise digitisation, factory automation, AI-enabled manufacturing, logistics and broader power infrastructure investment, with AI datacentre projects also expected to expand beyond Tokyo and Osaka as costs rise. Earnings have consistently beaten initial OP guidance in recent years. Toenec has raised its MTP 2027 targets and is increasing investor engagement, while any Chubu Electric Power stake reduction could improve free float and governance perception.
Technology
The new market narrative is focused on Arm’s AGI CPU strategy, under which the company targets $15bn of additional FY31 revenue, but AlphaValue sees major execution, customer and market risks. FY26 revenue grew from $4bn to $4.9bn but was heavily supported by related-party licensing and services revenue from a SoftBank affiliate, while external licensing revenue declined. Margins also remain far from the FY31 model: non-GAAP operating margin has stayed in the low-to-mid 40% range, while GAAP margins are significantly lower once share-based compensation is included. AlphaValue also questions whether selling server CPUs risks competing with Arm’s own licensees and undermining its neutral IP model. Even assuming management’s FY31 targets, the shares trade around 40x highly optimistic 5-year-forward EPS vs. 230x current P/E. The stock is disconnected from fundamentals. TP $97.8 (70% downside).
Consumer Staples
The group is caught in no man’s land as the hypermarket format structurally declines and Dutch hard-discounter Action (920 stores across France) dismantles the mid-market. Across virtually every European consumer sector since early 2026, the pattern is uniform: shoppers are aggressively trading down. Inflation has destroyed pricing power. Pierre-Olivier Essig remains sceptical of Alexandre Bompard’s strategy, viewing it as a weaker imitation of E.Leclerc’s model. The dividend is also viewed as increasingly vulnerable. Ahead of H1 results on 23rd July, Pierre forecasts 2026 operating margin down 25bps and top-line/EBIT down 4% LFL. TP €11 by end-2026 (30% downside). Pierre presented his short thesis at our latest Best Equity Short Ideas Conference - click here to listen.
Industrials
An under-covered Japanese small-cap (Asymmetric has been the only one highlighting this stock over the last few years) benefiting from ageing domestic industrial assets, decarbonisation investment, renewed focus on energy security and a shrinking pool of nationwide plant engineering providers (according to management, only Raiznext and Sankyu now have nationwide petrochemical coverage, together controlling c.50-60% of the market). The company has beaten its initial operating profit guidance for each of the past five years, including FY25 OP of ¥14.7bn, 36% above its initial target. Although FY26 guidance implies a 12% decline to ¥13bn, Asymmetric sees this as conservative given management tends to forecast only on projects already in hand. The shares trade on c.13x P/E with a 5.2% yield, while ENEOS’s 28.7% stake creates potential corporate-action optionality.
3 (non-AI) trillion-dollar trends
As we hit the near term financial and physical limits on AI spend, Erik@YWR shifts his focus to 3 non-AI themes with trillion-dollar potential. First, a prolonged state of insecurity in the Persian Gulf could force a structural re-architecture of global energy supply, benefiting alternative routes, LNG, refining, chemicals and infrastructure plays outside the Middle East (e.g. Turkey, Nigeria, US). Second, higher inflation and interest rates could extend the outperformance of DM banks, which remain cheap, under-owned and increasingly important in funding data-centre capex and new energy infrastructure. Third, China, which nobody owns and is at an earnings inflection point. Erik also wonders if Chinese construction companies could benefit from the rearchitecting of the world energy supply or Hong Kong as a financing hub for new infrastructure.
Tanzania: Stuck on stocks, better on flows
Buoyed by higher gold export prices and tourism revenues, Tanzania has made its way to broad external balance on the "basic" BOP front, which in turn has allowed it to stabilize the shilling and lower interest rates. Jonathan Anderson points out that the main risks here are higher oil import costs and a potential reversal in metals markets, but for the time being the country is holding the line. This still leaves Tanzania with a very high stock of external sovereign liabilities relative to dollar earnings, i.e., the country is effectively "stuck" on a long-term treadmill of IMF and other multilateral refinancing support and restructuring of bilateral obligations. The only good news here is that market participation in Tanzania's dollar debt burden is close to zero, which reduces pressure on rates and funding flows during the adjustment process.
Greek Equities: Adopting a more cautious stance
ResearchGreece revisits their stock picks and assesses the political outlook ahead of the next parliamentary elections. Macro conditions remain solid, with Q1 real GDP up 2.0% Y/Y, although inflation accelerated to 5.2% Y/Y in May (+0.0% M/M). With the Athens Index up +11% YTD, valuation multiples of non-banks in their universe have expanded to 13.2x P/E and 8.0x EV/EBITDA 2027, leaving more limited upside. Combined with polls pointing to a hung parliament, ResearchGreece is turning more cautious on Greek equities. Banks remain their preferred exposure (solid outlook - volume, rates, asset quality) as a leveraged Greek macro play. They prefer National Bank of Greece, Bank of Cyprus, Piraeus and Optima. Outside banks, they favour selective infrastructure, industrial and defensive names such as OTE, Titan, PPC and Piraeus Port over consumer stocks and cyclicals.
Industrials
ABM’s 2Q EPS beat was driven by stronger-than-expected revenue growth, with sales up 8.4% Y/Y and gains across all five segments for the fifth consecutive quarter. Technical Solutions, Aviation and Manufacturing & Distribution each grew by more than 15%, supported by organic gains and acquisitions. Sidoti’s FY26/FY27 EPS estimates of $4.03/$4.55 imply annual growth of 17.0% and 13.0%, respectively, while their FCF per share estimates of $4.25/$4.42 imply FCF yields of 10.0%/10.4%. ABM’s shares have traded at an average premium of 5% over the last 20 years to the S&P Small Cap 600 Index on a forward P/E basis but currently trade at a 34% discount. Sidoti maintains their Buy rating and $68 target, implying c.50% upside.
Industrials
EFN’s ~25% share price pullback over the past six months reflects concerns around lagging services revenue, moderating originations and potential AI disruption, but Veritas argues the fundamental impact is being overstated. Services revenue should recover as growth in Vehicles Under Management drives demand with a 12-15 month lag, while softer origination volumes have been offset by higher net financing revenue yields and growth in serviced-only VUMs. AI risk appears manageable, with the most exposed services representing only ~20% of annual delivery, while higher-touch offerings remain more defensible. Despite EFN’s stronger ROE profile, the stock trades below its five-year average P/E of 16.5x. They expect ROE to expand into the low-20% range and believe EFN's valuation multiple should re-rate as services revenue grows to the HSD range.
Defence Supply Chains: Hidden chokepoints, mispriced risk
The Iran conflict is not a regional event - it is a structural accelerant for the global Defence-Industrial Base. OMNISIGHT maps three converging chokepoints: China's gallium export controls (directly threatening F-35 radar integration timelines), Hormuz-driven sulphur disruptions cascading into propellant supply chains, and Qatar helium export risk affecting precision electronics. Combined, these create a butterfly chain that materially compresses production cadences for Tier-1 contractors in H2 2026 - a risk the market is currently underpricing. OMNISIGHT's institutional divergence analysis yields explicit ratings: Accumulate Lockheed Martin and BAE Systems; Hold RTX and Northrop Grumman; Reduce Rheinmetall, where a P/E of 90-100x leaves zero margin for delivery disappointment.
Where’s China’s fiscal crisis?
Things continue to look absolutely awful on the Chinese public sector front. Not only is China already one of the most heavily indebted economies in the EM universe, it also runs ever-widening public deficits. Then there’s the looming pension crisis. In short, claims Jonathan Anderson, this appears to be a disaster in the making. So, why haven’t things exploded? On the one hand, there are already growing austerity pressures in the economy, as local governments hike levies and fees on businesses and push for higher pension contributions. I.e., the fiscal mess is already becoming a drag on activity and growth. At the same time, however, there is no sign of budgetary funding stress. Why? Because the government completely controls both funding costs and flows via its state-owned monopoly in the commercial banking system, which in turn holds virtually all fiscal and "quasi-fiscal" debt. The real question is about the health of banks, not budgets.
US: Warsh’s natural bias
In the last week markets have moved to peg the Fed for about 28bps of hikes in the next year, a substantial shift from the 1-2 cuts priced in late February. Warsh assumes the Chair with a challenge to his natural bias – higher productivity via AI implying stronger GDP growth potential (but less inflation and hence need to hike), weak jobs markets but immigration arguably keeping the U/E rate down (which should point to rate cuts), a tighter and smaller Fed balance sheet (that implies rate cuts to offset) and different measures of inflation (trimmed mean over core PCE which conveniently is lower and implies rate cuts). This set of biases imples that Warsh is more of a cutter than a hiker. While the markets peg the first Fed hike in March 2027, Craig Ferguson thinks that the Fed will get an inflation shock in the next 3-4 months that leads to them hiking in Q3.
AI and Say's Law
Without a doubt, AI is a transformative tech with a strong future. However, Andrew Hunt says that some of the markets’ assumptions appear wayward to him. To “believe” in the AI Boom and in current market valuations, one must assume that the risk-free rate in the economy is at an equilibrium level currently; that there is minimal misallocation of capital occurring; that this is not simply just another credit boom; that forecast rates of likely AI take-up are accurate; and that Say’s Law will prevail (i.e. supply will create demand). Andrew finds evidence that many of these preconditions have likely already been invalidated. In previous manias, the “bell-was-rung-at-the-top” by often esoteric events within the plumbing of the credit system. It remains to be seen whether Mr Warsh will begin a quantitative tightening in the face of rising inflation, or bow to the political realities.
Technology
DSG combines one of the logistics software industry’s strongest network-effect moats with a highly disciplined acquisition strategy. The key differentiator is the company's proprietary Global Logistics Network, which processes >24bn transactions annually and embeds DSG deeply into mission-critical compliance and supply-chain workflows, supporting gross retention in the mid-to-high 90% range and NRR above 100%. Management’s acquisition track record is also underappreciated, with 34 deals completed since 2016 generating >15% RoAIC while maintaining a conservatively financed balance sheet. Based on 12% annual revenue growth, stable‑to‑expanding margins, and an exit NTM non‑GAAP P/E of 22x, 2Xideas forecasts mid‑teens annualised total shareholder returns through FY33E.
US S&P: Feeling good
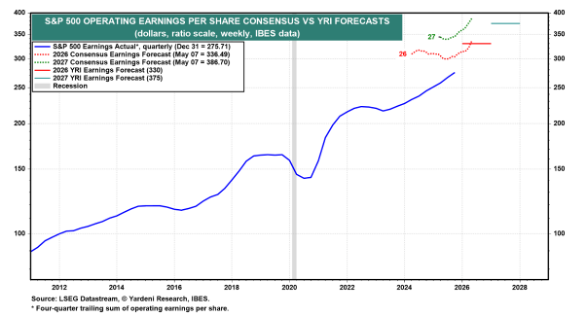
Ed Yardeni is raising his year-end S&P 500 target from 7700 to 8250. He has never seen consensus earnings expectations rise so quickly for the current and coming years as they have in recent months. The result has been an earnings-led meltup in the stock market. Ed is raising his EPS estimates to $330 this year and $375 next year, while sticking with his forward P/E range of 18.0-22.0, resulting in a year-end range for the S&P 500 of 6750-8250. His key assumption is that the economy will remain resilient, and so will earnings. Ed is also raising his probability of a continuation of the Roaring 2020s to 80% from 60% simply by merging it with his meltup scenario (previously at 20%), since he believes that any meltdown will be a buying opportunity and won't trigger a recession or bear market similar to the 1999-2000 Tech Bubble and Tech Wreck.
Consumer Staples
Sprouts Farmers Market reported encouraging 1Q26 results, reinforcing QuoVadis Research’s bullish stance. Revenue, same-store sales, margins, and EPS all modestly exceeded company guidance and Street expectations, suggesting management has regained control after the sharp slowdown experienced in 2H25. The company also deployed all 1Q26 free cash flow toward share repurchases, buying back 1.9M shares at an average price of $73.68, with QuoVadis modeling $500M in buybacks for full-year 2026. While guidance was largely maintained, the EPS outlook was slightly raised, signaling improved visibility. At just 13x P/E and 8x EV/EBITDA on consensus 2026 estimates, the stock undervalues Sprouts’ strong ROIC-driven growth and favorable risk-reward profile.
Innolight: AI optics leader targets H-Share listing
Technology
Aequitas offers an early look at Innolight as it aims to raise ~$5bn in an H-share listing (up from ~$3bn in late 2025), potentially making it one of Hong Kong’s largest deals this year. The company is the global leader in optical transceivers and is benefiting from strong demand driven by AI-related data centre capex. Growth has been exceptional, with revenue up 122% in 2024, 61% in 2025 and a further 192% YoY in 1Q26, alongside margin expansion. With revenue heavily concentrated among hyperscalers and shares already trading at elevated multiples (~37x FY26 P/E), the key question for investors is how much of this growth is already priced in.
Industrials
2Xideas latest deep-dive focuses on APG - a high-quality compounder, supported by market leadership and durable advantages in a regulation‑driven, non‑discretionary end market. Demand for fire protection inspection and maintenance is underpinned by stringent compliance requirements, while low customer cost supports pricing resilience. The group differentiates through national scale, premium service and investment in skilled labour. With significant consolidation runway and a proven M&A playbook, APG is well‑positioned for sustained DD earnings growth. 2Xideas forecasts revenue growth of 7.4% p.a. (2025-2032E), adjusted EBITDA margins rising from 13.2% to 17.9% and cumulative FCF of $7.8bn (~45% of m/cap). Applying a 20x exit NTM P/E 2032E, they estimate total shareholder returns of 12.9% p.a. over this period.
Industrials
Grid constraints threaten to slow data centre construction growth, potentially disrupting STRL’s key revenue growth and margin expansion engine. Early signs are already visible, with decelerating construction data, softer backlog and margin pressure in its core E-Infrastructure segment. The CEC acquisition is a desperate move by management to mask a plateau in its site prep business and expand into Texas ahead of increasing competition. With cash flow moderating (and diverging meaningfully from adjusted earnings), insider selling rising and valuation elevated (~22x EV/EBITDA), OWS is targeting more than 30% downside.
Materials
GMR upgraded KGH to Buy, following the recent pullback, arguing the stock offers a cheaper, lower-risk way to gain silver exposure. KGH is a much larger silver producer than often appreciated, with silver contributing ~26% of 2026 revenues (rising to ~32% at higher prices), supported by stable production and assets in low-risk jurisdictions. GMR forecasts earnings to rise ~70% Y/Y, with a base case of $79/oz silver in 2026, falling to $52 and $47 thereafter. The stock trades on ~7.7x 2026 P/E and ~4.4x EV/EBITDA (vs. ~7-8x for peers), with ~6.3% FCF yield. Valuation becomes increasingly compelling above $60-70/oz silver. Additional support comes from net debt trending to zero by 2028 and declining royalty charges.
Equities downgraded to neutral
Sam Burns has downgraded equities to neutral and raised cash in response to a deterioration in his indicators and increased macro risk and may do so further. Since the beginning of March when the US/Israel-led war in the Middle East started, his Equity Risk Model has deteriorated further, now below the 50% level and thus no better than neutral. While equity P/E ratios have declined, higher bond yields have largely offset the rise in earnings yields, leaving his Implied Growth Model still at elevated levels. Macro uncertainty has surged (again) and investors are focusing on how long and how bad the supply disruption in the Middle East will be – markets expect just a few months, but that timeline is gradually lengthening as escape routes for Trump are reduced. The positives are that earnings estimates are holding up so far, and short-term oversold conditions are in place.
Communications
While the market treats APP as an AI play, Andrew Freedman sees it is an infrastructure monopoly story. APP’s true moat is MAX, its mediation platform controlling >60% of mobile gaming impressions and supplying the auction data that powers AXON - without it, AXON’s performance is materially weaker. Andrew’s analysis includes how the company's 2025 game divestiture created a structural data deficit; why the identity graph is more fragile than the market appreciates; how E-Commerce scaling faces a bifurcated reality; why the mediation monopoly is under attack and the spread is unsustainable; and, how the regulatory cascade creates asymmetric downside.
Technology
The group's competitive moat is anchored by three mutually reinforcing advantages: 1) a proprietary, cloud‑native payments infrastructure with direct integrations into 50+ national payment systems across the world, creating a durable cost leadership position that compounds with scale; 2) a Mission Zero pricing philosophy, that continuously reinvests operational efficiencies and scale benefits into lower prices, driving organic volume growth and deepening customer stickiness; and 3) a growing platform business, which is transforming potential competitors into distribution partners, expanding the company's netting pool and lowering unit costs across the entire network. 2Xideas forecasts 14.7% revenue CAGR and 15.9% underlying income CAGR to FY32E. Assuming a conservative 20x exit NTM P/E, this supports ~17.5% annualised TSR.
Consumer Discretionary
John Zolidis’ investment case is based on a positive inflection in same-store sales producing valuation expansion as investors give more credit to unit growth and the longer-term opportunity. He believes this thesis remains intact as comps improved to -1.4% in FY25 (vs. -5.1% in FY24) and have turned positive in early FY26, with Q1 likely >2%. While the recent >10% share price drop reflects macro concerns and weak transaction trends (-6.4% in Q4), John views this as partly intentional, driven by ~10% price increases and a shift towards higher-income customers. This mix shift should support higher gross profit per ticket despite lower traffic. With the shares trading at 8x P/E and 5x EV/EBITDA (FY26 estimates) and a 9% FCF yield, ASO is a “bargain”, with an eye towards the upcoming analyst day as a near-term positive catalyst.
Communications
While the company likes to describe itself as strongly cash generative, FY25 results tell a different story. Cash inflow from operating activities fell sharply from £333m to £202m. Forensic Alpha also identified several other red flags, pushing ITV’s Risk Score from '8' to '10' (max. rating). Working capital has been a persistent drag, with the headwind widening from £144m in 2024 to £196m in 2025. Trade receivables rose 12% to £500m despite flat sales, driven largely by long-term balances now representing 18% of the total. Contract assets increased 33%, including a jump in non-current contract assets from £4m to £39m. Meanwhile, exceptional charges related to restructuring and M&A rose from £65m to £107m, further weighing on cash flow. For now, the market is focused on the potential sale of the M&E business. If it falls through, attention will shift back to the company’s underlying fundamentals.
Start slowly closing oil positions on any further rise in price
William (Buff) Brown observes that the US/Israeli-Iranian conflict has spread throughout the region with major interruptions in oil transit in the Arabian Gulf, with Iranian missile strikes in neutral Gulf countries, i.e. Oman, Bahrain, UAE, etc. While most were strikes directed against US assets, there were also strikes against civilian areas. With regard to oil transit, Iran has claimed that the Strait of Hormuz is effectively “closed”. However, it is not closed in the sense that Iran is, as of yet, targeting vessels en masse and/or has mined the 2-mile-wide outbound channel. The situation remains highly dynamic, however, and could change one way or another at any time. In any event, with the prompt NYMEX crude oil contract trading above $70.00 per barrel, he suggests maintaining the status quo for the time being, but on any further material price strength slowly begin closing out long positions. He does not recommend going short as prices rise.
South Korea: Words of warning
Jonathan Anderson observes that Korean equities shot up another 50% in the first two months, making Korea the best-performing market on the planet in 2026 so far. He notes that this is heavily due to the AI boom and Samsung, but "domestic Korea" has continued to rally this year as well. However, there's still no support from domestic macro. As before, Korea's economy is flatlining or contracting almost everywhere he looks: durables, construction, retail, credit, earnings. And while exports are rebounding, memory prices still haven't been able to bring Korea back to the EM-wide average trend. Jonathan says it will be hard to motivate further gains in local names. Equity multiples have already eliminated the famed "Korea discount" and continue to rise at the margin, i.e., corporate reforms have already been priced in well in advance of actual results - and there's no sign that the rally is boosting earnings and growth potential as of yet.
Approaching peak AI hysteria
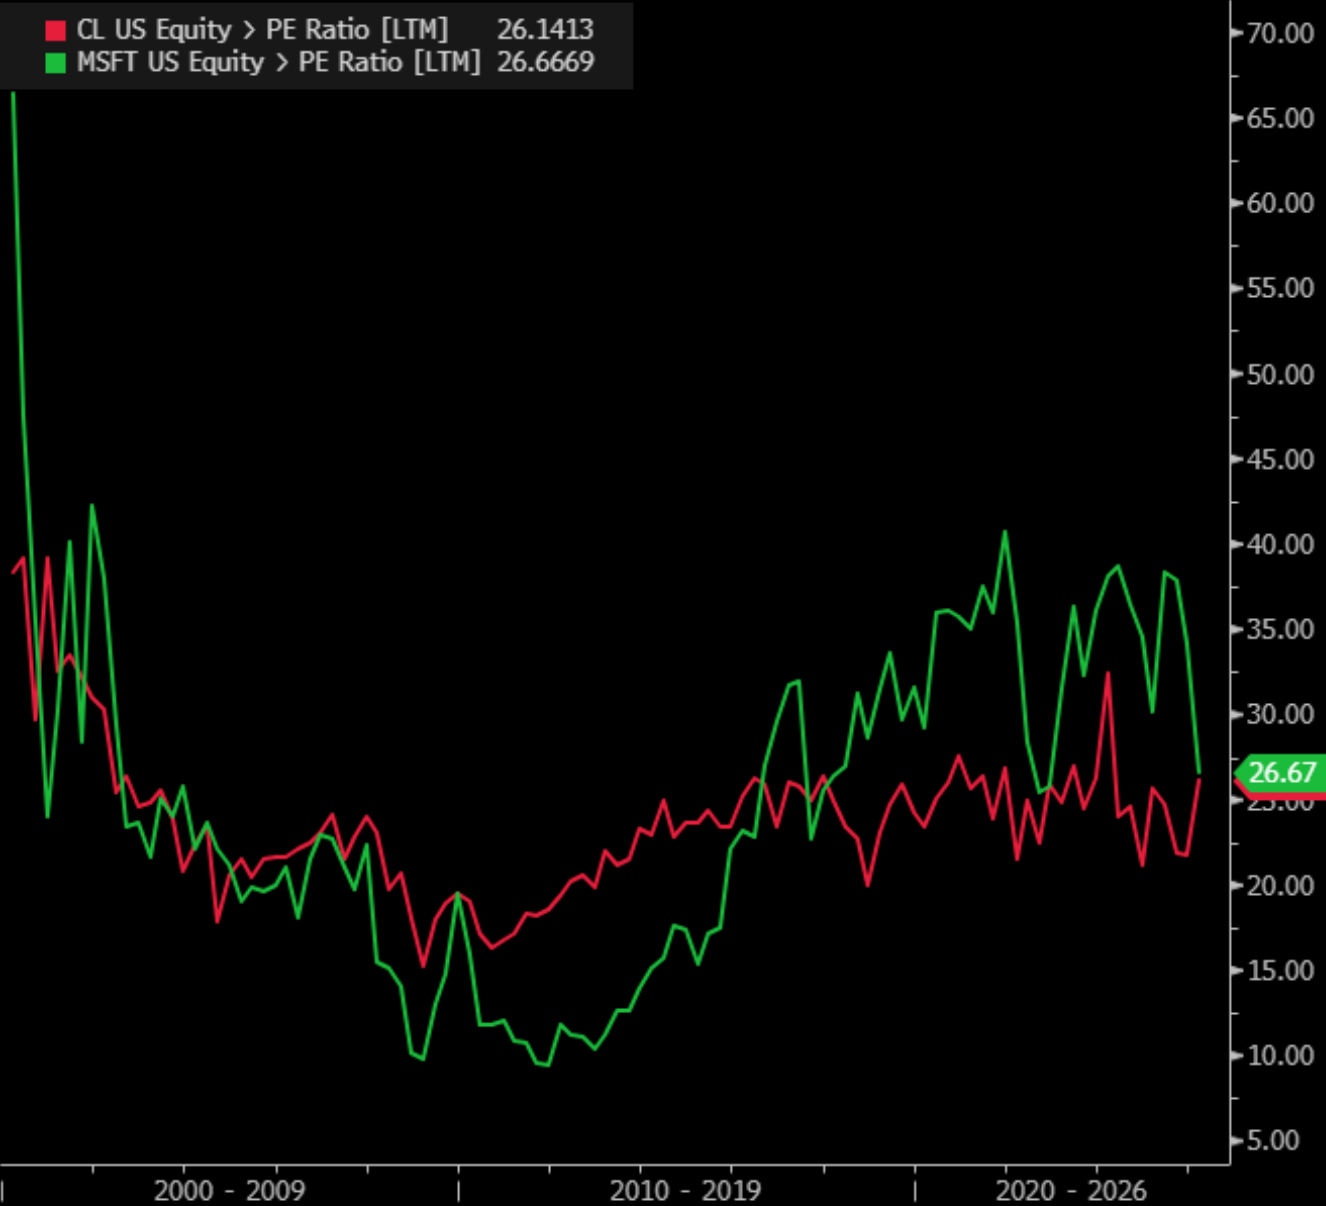
People are gregarious and instinctively follow the impulses of the herd, remarks James Aitken. The past two weeks have been a reminder of the mob mentality, and with dystopian projections on AI hysteria reaching millions of views, James believes we are approaching peak AI hysteria. Just remember when scouring the news: why am I reading this now and who benefits? XAI, Anthropic and OpenAI are all in windows to raise absurd amounts of money at lofty valuations, so it’s no surprise everyone is getting almost daily updates on LLMs about their improvements. DRAM, NAND and H100 rental prices suggest the AI juggernaut and associated memory shortage continues, yet so violent has been the recent shakedown that companies that would seem to have little risk of being disrupted by AI have been smashed, too. Just look at the current P/E of Microsoft (green) vs the current P/E of Colgate (red).
Energy
A large-cap trading at just ~11x earnings, with a ~12% FCF yield and will pay owners a 10% yield in the very near future. The Coterra deal markedly increases DVN’s stature and shale production in the Delaware Basin without incremental acquisition debt, adding ~4,600 high-return drilling locations, nearly half with sub-$40/bbl breakevens. The combined company expects $1bn+ in annual synergies and plans a $5bn buyback, materially lifting FCF/share and NAV/share. Nevertheless, investors have yet to adequately reflect DVN’s improved fundamentals in its share price, with it continuing to trade at a sharp discount to other E&P players in terms of both P/OCF and at a high required FCF yield. For each 0.5x improvement in its P/OCF multiple or a 1pp decrease in its FCF yield, DVN’s share price will rise by ~$5.
Gross margins are rolling over, but net margin expectations remain high
Median gross margins for the Top 500 peaked at 46.4% in Feb 25 and have since fallen to 44.9% in Jan 26, yet bottom-up forecasts imply continued strong net income growth - likely reflecting embedded AI-driven productivity assumptions. Historically, Trivariate finds valuation multiples correlate more closely with gross profit growth than net income growth, implying further multiple expansion will require renewed gross margin strength or a structural shift in how markets reward earnings. Their quantitatively derived longs (e.g. Merck, T-Mobile, McDonald’s) have had recent multiple expansion and are forecasted to have margin expansion, but not more net margin than gross margin expansion. While shorts (e.g. Amphenol, Salesforce, Arista Networks, Las Vegas Sands) screen for gross margin contraction but net margin expansion, reducing estimate achievability.
Consumer Discretionary
The shift from puffer-only to broader fashion outerwear (wool, shearling, fur) has expanded consumers’ wardrobes, with MONC well positioned at the intersection of function and luxury. Its core styles are not overly trend-led, supporting their status as long-term investment pieces with resale value. Pricing sits above Canada Goose and Herno, but below Prada and Loro Piana, sustaining an attractive premium tier. Beyond outerwear, The Retail Tracker sees opportunity in functional yet fashionable handbags (e.g., a travel line between Rimowa and Away). Footwear remains strong but still lacks a viral breakout moment. Meanwhile, early signs of a streetwear revival could lift visibility for Stone Island and help the brand extend beyond its core. Under new leadership, renewed energy in the stock could support a move back towards the 52-week high.
The best FX trade for 2026
In Stephen Jen’s view, USDJPY may be the best (i.e., with the highest Sharpe ratio) FX trade for 2026. With the dominant election victory, Stephen points out that the LDP has enough popular support for PM Takaichi to go through with her 3%-GDP worth of fiscal stimulus. With inflation still above the BOJ’s target (headline CPI is down to 2.1%, but core-core is still hovering around 3.0%), this prospective fiscal stimulus will likely be met with accelerated or earlier rate hikes by the BOJ. Stephen says that the US Fed and the BOJ will continue to converge in 2026, with the former cutting while the latter is hiking. Stephen argues that the US dollar itself is in a structural descent, and the particular policy mix in Japan should lead to a stronger JPY. He still views 125 as a very reasonable target for USDJPY this year.
The Korea rally for 2026?
With the Korean index rallying through year-end, Jonathan Anderson examines the outlook. Part of the trend, of course, is the ongoing massive global IT boom. But, as before, the main story at home is the sharp rerating of the rest of the index; "domestic Korea" jumped dramatically over the past nine months on promises of corporate reforms. There's zero support from domestic macro. Korea's economy is flatlining or contracting almost everywhere Jonathan looks: durables, construction, retail, exports, credit, earnings. As a result, it's hard to motivate further gains. Korean multiples are already converging on EM-wide levels as the "Korea discount" narrows, i.e., reforms have already been priced in well in advance of actual results - and even in the strong success case this may not necessarily impact aggregate earnings and growth potential going forward. In short, at the macro level Jonathan doesn’t see significant upside potential from here.